WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Wednesday, 21 October 2026 | Vol. 2026-294 | As of 211230 EDT OCT 26 | First edition
First edition. Business WIRE scores the operating environment for firms: credit, AI-build-out financing, freight, trade policy and equity markets. Thresholds are starting proposals, to be recalibrated after 30 days. Facts are cited; inference is labeled Analyst Comment.
BLUF. WIRE Business opens at POTENTIAL CRISIS (↑), set by one topic: financing of the AI infrastructure build-out (BIZ-T2). CoreWeave's five-year CDS traded near 1,038 bp on 15 Oct (distress territory) and its 2031 bond yielded 15.78%, while an AirTrunk REIT, Firmus and SB Energy listings were pulled or paused within a week. The stress is concentrated in the borrowed-money tier: the S&P 500 is only 1.4% off its 6 Oct record (7,712.57), VIX is 17.31, and Q3 S&P 500 blended earnings growth is 29.0% (FactSet). Credit is decompressing at the tail, not the core: HY OAS 3.29% (19 Oct), but CCC spreads above 1,000 bp, the widest since 2023 (BIZ-T1 NO CRISIS ↑). Freight is elevated but easing on the Suez return: Drewry WCI $4,485/40ft (15 Oct), about 2.7× a year ago, with more than half of tracked container services back through Suez (BIZ-T3 ENVIRONMENT FOR CRISIS =). Trade policy is de-escalating at the margin (BIZ-T4 NO CRISIS ↓).
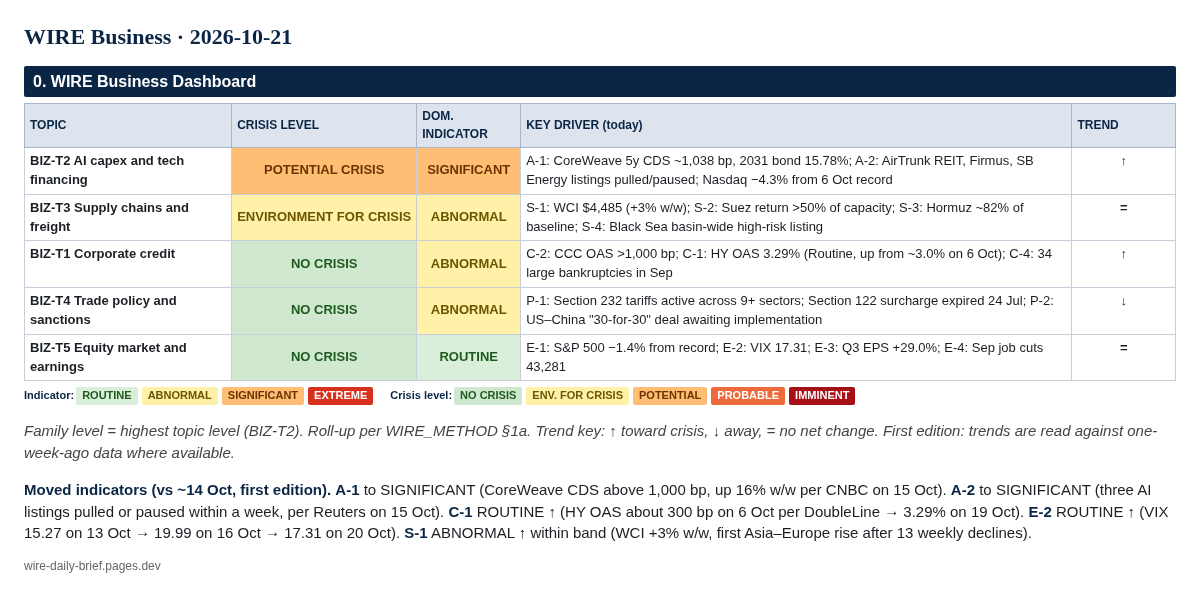
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-1: CoreWeave 5y CDS ~1,038 bp, 2031 bond 15.78%; A-2: AirTrunk REIT, Firmus, SB Energy listings pulled/paused; Nasdaq −4.3% from 6 Oct record | ↑ |
| BIZ-T3 Supply chains and freight | ENVIRONMENT FOR CRISIS | ABNORMAL | S-1: WCI $4,485 (+3% w/w); S-2: Suez return >50% of capacity; S-3: Hormuz ~82% of baseline; S-4: Black Sea basin-wide high-risk listing | = |
| BIZ-T1 Corporate credit | NO CRISIS | ABNORMAL | C-2: CCC OAS >1,000 bp; C-1: HY OAS 3.29% (Routine, up from ~3.0% on 6 Oct); C-4: 34 large bankruptcies in Sep | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1: Section 232 tariffs active across 9+ sectors; Section 122 surcharge expired 24 Jul; P-2: US–China "30-for-30" deal awaiting implementation | ↓ |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −1.4% from record; E-2: VIX 17.31; E-3: Q3 EPS +29.0%; E-4: Sep job cuts 43,281 | = |
Family level = highest topic level (BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change. First edition: trends are read against one-week-ago data where available.
Moved indicators (vs ~14 Oct, first edition). A-1 to SIGNIFICANT (CoreWeave CDS above 1,000 bp, up 16% w/w per CNBC on 15 Oct). A-2 to SIGNIFICANT (three AI listings pulled or paused within a week, per Reuters on 15 Oct). C-1 ROUTINE ↑ (HY OAS about 300 bp on 6 Oct per DoubleLine → 3.29% on 19 Oct). E-2 ROUTINE ↑ (VIX 15.27 on 13 Oct → 19.99 on 16 Oct → 17.31 on 20 Oct). S-1 ABNORMAL ↑ within band (WCI +3% w/w, first Asia–Europe rise after 13 weekly declines).
Credit stress at the bellwether. CoreWeave has taken on more than $51B of debt and obligations for its AI build-out. Its 9.75% 2031 bond traded to a 15.78% yield to maturity, and its five-year CDS spread topped 1,140 bp intraday before settling near 1,038 bp, up 16% on the week. S&P Global Market Intelligence's Gavan Nolan said a spread of 1,000 bp or more is generally a sign of distress (CNBC, 15 Oct). Bonds issued in June at 9.675% traded to a 15% yield that week (Reuters via Investing.com, 16 Oct). Financing pulled. Listings for a Blackstone-backed AirTrunk REIT, Nvidia-backed Firmus and SoftBank-backed SB Energy were pulled or paused within one week (Reuters via Investing.com, 15 Oct). South Korean neocloud Elice fell more than 30% in its 20 Oct trading debut (Axios, 21 Oct). Equities. The Nasdaq Composite closed at 26,424.82 on 20 Oct, 4.3% below its 6 Oct record of 27,599.79 (Reuters via StreetInsider, 20 Oct; CNBC, 6 Oct). WSJ described the 20 Oct session as strong earnings offsetting "worries about the sustainability of the debt-fuelled artificial-intelligence boom" (WSJ, 20 Oct). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT. A-3 ROUTINE (−4.3%). A-4 not collected (SOX). A-5 ROUTINE (no hyperscaler capex cut found; Q3 reports pending). Roll-up: 2 Significant = POTENTIAL CRISIS. Tripwire (Imminent): A-1 at Extreme (missed payment or restructuring at a bellwether AI-infrastructure issuer) together with A-5 Significant. Analyst Comment. This is a credit-led repricing at the top of the AI capital stack, not a demand collapse. CNBC's sources say no one questions that demand is real, and the doubt is about whether cash flows arrive in time. Two things would move this toward Probable: stress spreading from the neocloud tier into hyperscaler borrowing costs or capex guidance (A-5), and a Nasdaq drawdown past 10% (A-3). Hyperscaler Q3 reports in the next two weeks are the key collection window.
Container rates. Drewry's WCI rose 3% to $4,485/40ft on 15 Oct. Shanghai–Rotterdam rose 6% to $3,522 and Shanghai–Genoa 7% to $3,945, the first Asia–Europe rise after 13 weekly declines. Shanghai–Los Angeles rose 3% to $7,884, and Shanghai–New York fell 1% to $10,075. Drewry expects stable rates and cites resumed Suez transits adding Asia–Europe capacity (Drewry, 15 Oct). Forwarders told The Loadstar that the 19 Oct FAK increases were already being revised down (Loadstar, 16 Oct). A year earlier the WCI stood near $1,687 (SplyLine's archive of Drewry readings, 17 Oct 2025 issue) (SplyLine). Chokepoints. More than half of tracked container services have returned to Suez routing, with weekly Suez capacity of 753,000 TEU in early October (above 50% of pre-disruption). A full return is not expected before Q1 2027 (World Ports Organization). Maersk and Hapag-Lloyd resume Suez routing for the AE12 service from 27 Oct (Ahram Online). Kpler puts 7-day Hormuz clearance at 14.1 mb/d, about 82% of baseline (Kpler, 20 Oct; see WIRE World Instability W-1). In the Black Sea, the London market's high-risk area now covers the whole sea except Romanian, Bulgarian and Turkish territorial waters (Guardian, 20 Oct). Indicators. S-1 ABNORMAL. S-2 ABNORMAL (50–80% band). S-3 ABNORMAL (82%, business flow lens; the attack tempo is scored in W-1). S-4 ABNORMAL (basin-wide listing). S-5 not assessed (no major US/EU port strike found). Roll-up: 4 Abnormal = ENVIRONMENT FOR CRISIS. Analyst Comment. Two forces offset each other, so the trend is =. The Suez return adds capacity and should pull Asia–Europe rates down. Hormuz flows are recovering mainly through workarounds. The Black Sea is the only lane getting worse.
Spreads. ICE BofA US High Yield OAS was 3.29% on 19 Oct (FRED BAMLH0A0HYM2, via MacroRadar), against about 300 bp on 6 Oct, when Caa spreads were 986 bp and Ba 177 bp. The Caa/Ba ratio of 5.57x ranks near the 99th percentile since 1994 (DoubleLine). CCC spreads are now above 1,000 bp, the highest since the 2023 regional-bank stress, with CCC yields at 15.58%. JPMorgan projects HY defaults of 2.25% in 2026, rising to 2.75% in 2027 (leveraged loans 4.50%) (The Edge, citing JPMorgan). Janus Henderson estimates about 20% of the CCC index traded at $60 or below in early October (Janus Henderson). Bankruptcies. S&P Global Market Intelligence counted 34 large US bankruptcy filings in September (49 in August), and 530 year to date against 577 a year earlier (BeBankers, citing S&P GMI). Indicators. C-1 ROUTINE (↑). C-2 ABNORMAL. C-3 not verified (one secondary source puts IG OAS at 90 bp; see the unverified list). C-4 ROUTINE. C-5 and C-6 not collected. Roll-up: 1 Abnormal = NO CRISIS. Analyst Comment. Stress is still a tail event: the lowest-rated borrowers face refinancing walls at 15%+ yields while BB credit is near 20-year tights. The warning sign to watch is C-1 crossing 350 bp, which would mean the widening has moved up the ratings ladder. BIZ-01 tests that.
Tariffs. CRS's 8 Oct fact sheet says the 10% Section 122 import surcharge, imposed in February, expired on 24 Jul after its 150-day statutory period. The administration continues to rely on Section 232 (steel, aluminum, autos, copper, pharmaceuticals, semiconductors, timber, drones, polysilicon) and on Section 301 (CRS R49481, 8 Oct; White House proclamation, Feb 2026). US–China. China's Commerce Ministry briefed on the outcomes of the eighth round of China–US consultations, a "30-for-30" arrangement covering about $30B of goods each way, with implementation pending domestic procedures (MOFCOM; Caixin, 1 Oct). Indicators. P-1 ABNORMAL (broad sector tariffs standing; no new across-the-board action). P-2 ROUTINE (truce pending implementation). P-3 not collected. P-4 ROUTINE (oil markets are weighing a potential US waiver on Russian energy, per Reuters via Investing.com on 20 Oct; no new sanctions shock found). Roll-up: 1 Abnormal = NO CRISIS (↓).
On 20 Oct the S&P 500 closed at 7,712.57 (+0.28%), 1.4% below its 6 Oct record close of 7,818.93, and the Dow rose 1.02% to 52,495.88, helped by 3M (+5.8%) after it expanded a data-center partnership with Amazon and raised guidance (Reuters via StreetInsider; Morningstar/Dow Jones, 6 Oct). VIX closed at 17.31 after a 19.99 high close on 16 Oct (FRED VIXCLS). FactSet puts Q3 S&P 500 blended earnings growth at 29.0% as of 16 Oct (FactSet). Challenger counted 43,281 announced US job cuts in September, down 20% y/y (Challenger, Sep 2026). Indicators. E-1 ROUTINE. E-2 ROUTINE. E-3 ROUTINE. E-4 ROUTINE. E-5 ROUTINE. Roll-up: NO CRISIS (=). The 10-year Treasury at 5.12% is scored in WIRE Economics (ECO-T1).
CNBC (15 Oct); Reuters via Investing.com (15–16 Oct); Axios (21 Oct); Reuters via StreetInsider (20 Oct); WSJ (20 Oct); CNBC and Morningstar/Dow Jones (6 Oct); Drewry WCI (15 Oct); The Loadstar (16 Oct); SplyLine; World Ports Organization; Ahram Online; Kpler media briefing (20 Oct); The Guardian (20 Oct); MacroRadar/FRED; DoubleLine; The Edge/JPMorgan; Janus Henderson; BeBankers/S&P Global MI; CRS R49481 (8 Oct); White House; MOFCOM; Caixin (1 Oct); FRED VIXCLS; FactSet (16 Oct); Challenger, Gray & Christmas.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe