WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Friday, 23 October 2026 | Vol. 2026-296 | As of 230640 EDT OCT 26
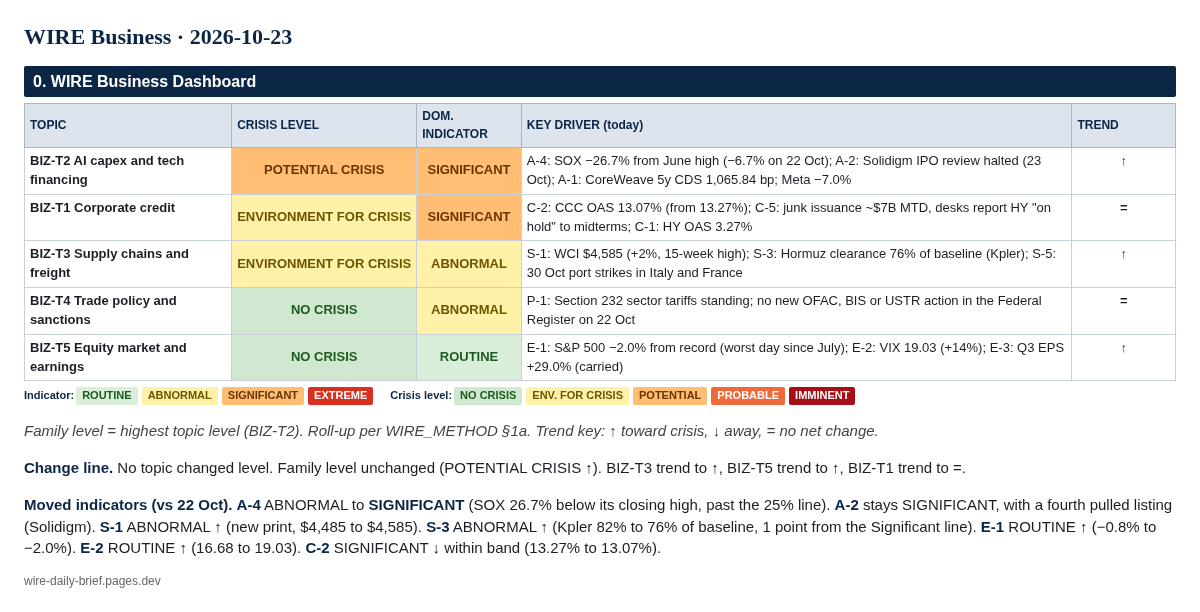
BLUF. WIRE Business holds at POTENTIAL CRISIS (↑), and AI-infrastructure financing (BIZ-T2) now has three indicators at Significant. The PHLX Semiconductor Index fell 6.72% to 10,731.98 on 22 Oct, 26.7% below its June closing high (FRED). SK hynix said on 23 Oct that Solidigm has halted its US IPO review, citing market conditions. CoreWeave's five-year CDS was at 1,065.84 bp on 21 Oct (FactSet via CNBC). Meta fell 7.0% after reporting its first cash outflow in more than a decade and a plan to create a non-voting share class to help fund AI spending (Reuters). The Nasdaq fell 2.6% and the S&P 500 1.2%, its worst day since July, but both remain within 6% of their records. Corporate credit holds at ENVIRONMENT FOR CRISIS (=): CCC spreads eased to 13.07%. Freight edges up (↑): the Drewry WCI rose 2% to $4,585, and Hormuz flows slipped to 76% of baseline. Trade policy is unchanged at NO CRISIS.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX −26.7% from June high (−6.7% on 22 Oct); A-2: Solidigm IPO review halted (23 Oct); A-1: CoreWeave 5y CDS 1,065.84 bp; Meta −7.0% | ↑ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.07% (from 13.27%); C-5: junk issuance ~$7B MTD, desks report HY "on hold" to midterms; C-1: HY OAS 3.27% | = |
| BIZ-T3 Supply chains and freight | ENVIRONMENT FOR CRISIS | ABNORMAL | S-1: WCI $4,585 (+2%, 15-week high); S-3: Hormuz clearance 76% of baseline (Kpler); S-5: 30 Oct port strikes in Italy and France | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1: Section 232 sector tariffs standing; no new OFAC, BIS or USTR action in the Federal Register on 22 Oct | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −2.0% from record (worst day since July); E-2: VIX 19.03 (+14%); E-3: Q3 EPS +29.0% (carried) | ↑ |
Family level = highest topic level (BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic changed level. Family level unchanged (POTENTIAL CRISIS ↑). BIZ-T3 trend to ↑, BIZ-T5 trend to ↑, BIZ-T1 trend to =.
Moved indicators (vs 22 Oct). A-4 ABNORMAL to SIGNIFICANT (SOX 26.7% below its closing high, past the 25% line). A-2 stays SIGNIFICANT, with a fourth pulled listing (Solidigm). S-1 ABNORMAL ↑ (new print, $4,485 to $4,585). S-3 ABNORMAL ↑ (Kpler 82% to 76% of baseline, 1 point from the Significant line). E-1 ROUTINE ↑ (−0.8% to −2.0%). E-2 ROUTINE ↑ (16.68 to 19.03). C-2 SIGNIFICANT ↓ within band (13.27% to 13.07%).
Chips. The PHLX Semiconductor Index closed at 10,731.98 on 22 Oct, down 6.72% on the day and 26.7% below its 22 Jun closing high of 14,634.72 (FRED NASDAQSOX). Reuters tied the sell-off to revived doubts about AI spending (Reuters via Investing.com, 22 Oct). Pulled financing. SK hynix said Solidigm will discontinue its review of pre-IPO and US IPO options after assessing capital-market conditions and share-price trends. It will look at other ways to fund a new US fab (SK hynix Newsroom, 23 Oct; also reported by Yonhap and CNBC). Bellwether credit. CoreWeave's five-year CDS was 1,065.84 bp on 21 Oct, per FactSet. Oracle's was 308.25 bp (141 bp on 2 Jan), and SoftBank's was about 432 bp (CNBC, 22 Oct). CoreWeave's 2031 bond yielded a record 15.76% on 22 Oct (Benzinga, 22 Oct; see also CNBC, 21 Oct). Hyperscaler funding. Meta fell 7.0%. Reuters says it posted its first cash outflow in more than a decade because of AI spending (Reuters via Investing.com, 22 Oct). Meta plans non-voting Class C shares, effective 19 Jan 2027, to help fund the expansion (Reuters, 21 Oct). The Nasdaq Composite closed at 26,008.86 (−2.60%), 5.8% below its 6 Oct record of 27,599.79 (FRED NASDAQCOM). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT. A-3 ROUTINE (−5.8%). A-4 SIGNIFICANT (−26.7%). A-5 ROUTINE (no hyperscaler cut; Tesla's capex cut is not a hyperscaler). Roll-up: 3 Significant, no Extreme = POTENTIAL CRISIS (↑). Analyst Comment. The move to Probable needs an Extreme: a missed payment or restructuring at a bellwether (A-1), SOX more than 40% below its high (A-4), or a hyperscaler or anchor lender cancelling committed capex (A-2). None of these is close today. Still, with three Significant readings in one cycle, this is now a cluster under the EWC proposal. The market is no longer only repricing the weakest borrowers: a hyperscaler (Meta) is turning to a new equity class, and a memory maker has shelved a listing to fund a US fab. That points to AI capital becoming scarcer, not just dearer at the margin.
Spreads (FRED, read directly). HY OAS 3.27% on 21 Oct (3.33% on 20 Oct) (BAMLH0A0HYM2). CCC OAS 13.07% (13.27%) (BAMLH0A3HYC). IG OAS 0.88% (BAMLC0A0CM). Primary market. US junk-bond sales are still about $7B month to date, against $51B in September, and more than $5B of US and European deals have been postponed this month (Bloomberg via Advisor Perspectives, 21 Oct). Sources on credit desks told CNBC the high-yield market is "effectively on hold until after the midterm elections" (CNBC, 21–22 Oct). Blackstone rose 8.4% after saying wider spreads on AI-related debt could let it lock in higher returns (Reuters, 22 Oct). Private credit. Fitch tracks 15 non-traded BDCs that reported Q3 tenders. Thirteen saw smaller redemption requests than in Q2, but nine were still above their 5% quarterly caps and prorating. The average request was 9.8% (FinancialMarkets.com on Fitch, 14 Oct). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (34 in Sep, carried). C-5 ABNORMAL. C-6 ABNORMAL. Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. C-6 is borderline. Nine funds prorating could read as "gates at 3+ funds" (Significant). We score it Abnormal because these are standing 5% tender caps, not new suspensions, and requests are falling at 13 of 15 funds. If C-5 or C-6 were scored Significant, BIZ-T1 would reach POTENTIAL CRISIS. Spreads eased on the day, so the trend is =.
The Drewry WCI rose 2% to $4,585/40ft on 22 Oct, its second weekly rise and a 15-week high. Shanghai–Rotterdam rose 3% to $3,632, and Shanghai–Los Angeles rose 2% to $8,007. Drewry counts 55 Suez sailings in week 42 (54 in week 41) and only two containerships entering the Gulf (five the week before) (Drewry, 22 Oct). Kpler's 22 Oct briefing puts the 7-day Hormuz clearance at 13,047 kbd, about 76% of baseline (82% before), and Red Sea loadings at about 89% above baseline (Kpler, 22 Oct; see WIRE World Instability). The 30 Oct port strikes in Italy and France are still called (Ports Europe). Indicators. S-1 ABNORMAL (↑). S-2 ABNORMAL. S-3 ABNORMAL (↑, 24% below baseline against a 25% Significant line). S-4 ABNORMAL (carried). S-5 ABNORMAL. Roll-up: 5 Abnormal = ENVIRONMENT FOR CRISIS (↑). Analyst Comment. The Houthi campaign against Saudi Arabia (WIRE World Instability, W-2) threatens the Red Sea bypass that carries the oil diverted from Hormuz. A confirmed strike on Red Sea shipping or Yanbu would move S-2 and S-3 at the same time.
OFAC's last action was on 21 Oct (OFAC, 21 Oct). No new action was posted for 22 Oct (OFAC recent actions). The Federal Register API shows no USTR or BIS documents published on or after 22 Oct (Federal Register API). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: 1 Abnormal = NO CRISIS (=).
The S&P 500 fell 1.21% to 7,663.43, 2.0% below its 7,818.93 record. The Dow rose 0.02% to 52,867.98 (Reuters, 22 Oct; AP). VIX closed at 19.03, up 14.1% (WSJ, 22 Oct; Yahoo Finance). The 10-year Treasury yield fell below 5%, down nearly 0.2 percentage point, which WSJ called the sharpest one-day drop in more than three years (scored in WIRE Economics). FactSet's blended Q3 EPS growth is carried at 29.0% (16 Oct). Its next update is due today (FactSet). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (↑).
None resolved today. - BIZ-01 (HY OAS ≥ 3.75%): 3.27%, not met. - BIZ-02 (WCI ≤ $4,300 by 12 Nov): WCI rose to $4,585; trending miss. - BIZ-03 (S&P 500 record above 7,818.93): 2.0% short. - BIZ-04 (CCC OAS ≥ 14.00%): 13.07%, not met. - BIZ-05 (SOX ≤ 10,976.04, window 23 Oct–20 Nov): the 22 Oct close of 10,731.98 is below the line, but it falls one day before the window opens, so it does not count. A close at or below the line from today resolves it a hit.
New (dated 2026-10-23; logged in the prediction ledger): - BIZ-06: The Nasdaq Composite (FRED NASDAQCOM) closes at or below 24,839.81 (10% below its 6 Oct record of 27,599.79, the A-3 Abnormal line) on any trading day from 23 Oct to 20 Nov 2026. 35%, unlikely. Resolve by 2026-11-20. - BIZ-07: A Drewry WCI composite published from 29 Oct to 19 Nov 2026 is at or above $5,000/40ft. 20%, unlikely. Resolve by 2026-11-19.
FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS, SP500, NASDAQCOM, NASDAQSOX); Reuters via Investing.com (21–22 Oct); AP (22 Oct); CNBC (21–22 Oct); Benzinga (22 Oct); SK hynix Newsroom, Yonhap and CNBC (23 Oct); Bloomberg via Advisor Perspectives (21 Oct); FinancialMarkets.com/Fitch (14 Oct); Drewry (22 Oct); Kpler media briefing (22 Oct); Ports Europe; OFAC; Federal Register API; WSJ (22 Oct); Yahoo Finance; FactSet (16 Oct).
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe