WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Saturday, 24 October 2026 | Vol. 2026-297 | As of 240640 EDT OCT 26
BLUF. WIRE Business holds at POTENTIAL CRISIS (↑), with stress spreading from AI financing into credit and freight. The PHLX Semiconductor Index closed at 10,779.46 on 23 Oct, 26.3% below its June high, which resolves BIZ-05 a hit (FRED). Five-year CDS on Meta, Nvidia and Oracle reached record spreads this week, and CoreWeave's stayed above 1,100 bp (CNBC). High-yield spreads widened to 3.40% and CCC spreads to 13.40% on 22 Oct (FRED). Kpler puts the 7-day Hormuz clearance at 74% of baseline, so freight indicator S-3 moves to Significant; Brent settled at $116.72, its highest since April. Stocks fell again on Friday (S&P 500 −0.52%, Dow −1.23%), but the S&P is only 2.5% below its record and Q3 blended earnings growth rose to 29.5% (FactSet). Trade policy stays at NO CRISIS; USTR has proposed extending the pause on its China shipping fees to 9 Jan 2027.
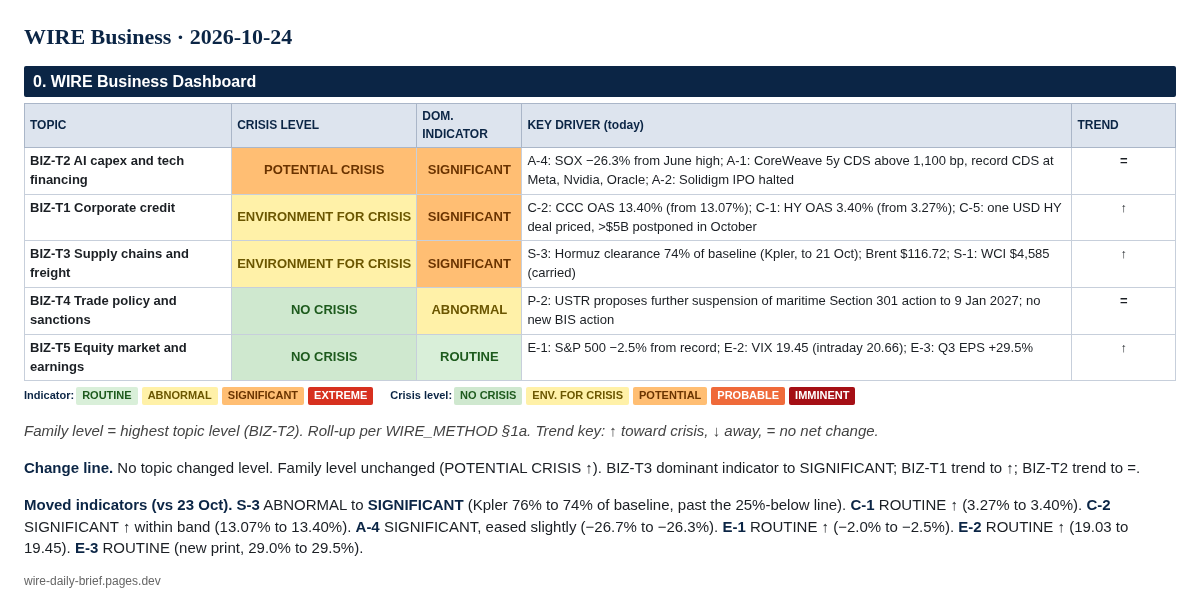
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX −26.3% from June high; A-1: CoreWeave 5y CDS above 1,100 bp, record CDS at Meta, Nvidia, Oracle; A-2: Solidigm IPO halted | = |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.40% (from 13.07%); C-1: HY OAS 3.40% (from 3.27%); C-5: one USD HY deal priced, >$5B postponed in October | ↑ |
| BIZ-T3 Supply chains and freight | ENVIRONMENT FOR CRISIS | SIGNIFICANT | S-3: Hormuz clearance 74% of baseline (Kpler, to 21 Oct); Brent $116.72; S-1: WCI $4,585 (carried) | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-2: USTR proposes further suspension of maritime Section 301 action to 9 Jan 2027; no new BIS action | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −2.5% from record; E-2: VIX 19.45 (intraday 20.66); E-3: Q3 EPS +29.5% | ↑ |
Family level = highest topic level (BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic changed level. Family level unchanged (POTENTIAL CRISIS ↑). BIZ-T3 dominant indicator to SIGNIFICANT; BIZ-T1 trend to ↑; BIZ-T2 trend to =.
Moved indicators (vs 23 Oct). S-3 ABNORMAL to SIGNIFICANT (Kpler 76% to 74% of baseline, past the 25%-below line). C-1 ROUTINE ↑ (3.27% to 3.40%). C-2 SIGNIFICANT ↑ within band (13.07% to 13.40%). A-4 SIGNIFICANT, eased slightly (−26.7% to −26.3%). E-1 ROUTINE ↑ (−2.0% to −2.5%). E-2 ROUTINE ↑ (19.03 to 19.45). E-3 ROUTINE (new print, 29.0% to 29.5%).
Chips. The PHLX Semiconductor Index closed at 10,779.46 on 23 Oct, up 0.4% on the day and 26.3% below its 22 Jun closing high of 14,634.72 (FRED NASDAQSOX). Micron and AMD gained about 3% and 2% as chip stocks steadied (CNBC, 23 Oct). Bellwether credit. CNBC reports CoreWeave's five-year CDS has widened past 11% (1,100 bp) and yields on its 2031 and 2032 unsecured notes topped 15%. Five-year CDS on Meta reached a record above 124 bp, and Nvidia and Oracle touched records of 126 bp and 343 bp this week (CNBC, 23 Oct). Morgan Stanley cut its CoreWeave price target to $70 from $99, citing "growing financing uncertainty" (CNBC, 23 Oct). Financing plans. Goldman Sachs quotes Oracle's FY27 funding framework as about $20B of equity (an at-the-market program, already executed), $20–25B of customer prepayments and about $20B of debt in the second half of FY27 (CNBC, 23 Oct). SK hynix's halt of the Solidigm IPO review (23 Oct) stands (SK hynix Newsroom). Nasdaq. The Composite closed at 25,955.34 (−0.21%), 6.0% below its 6 Oct record (CNBC; Reuters via Yahoo Finance, 23 Oct). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT. A-3 ROUTINE (−6.0%). A-4 SIGNIFICANT (−26.3%). A-5 ROUTINE. Roll-up: 3 Significant, no Extreme = POTENTIAL CRISIS (=). Analyst Comment. Record CDS at Meta and Nvidia matters more than the level: at about 125 bp these are still investment-grade prices, but protection buying has reached the strongest balance sheets in the trade, not only the leveraged neoclouds. The next test is hyperscaler capex guidance in the coming week's earnings (A-5). One cut would add an Abnormal; a cancelled committed financing would be Extreme.
Spreads (FRED, read directly). HY OAS 3.40% on 22 Oct (3.27% on 21 Oct) (BAMLH0A0HYM2). CCC OAS 13.40% (13.07%) (BAMLH0A3HYC). IG OAS 0.89% (BAMLC0A0CM). Primary market. Bloomberg reports junk-bond sales dropped sharply in October as investors demanded more yield, with the biggest spate of delayed deals this year (Bloomberg, 21 Oct). CreditFlow's 21 Oct close notes only one USD high-yield deal priced that day (CreditFlow). Private credit. No new gate or suspension found. Stanger reports NAV BDCs have returned about $5.6B to investors so far in Q3 (Stanger). Indicators. C-1 ROUTINE (↑, 10 bp below the 350 bp line). C-2 SIGNIFICANT (↑). C-3 ROUTINE. C-4 ROUTINE (34 in Sep, carried). C-5 ABNORMAL. C-6 ABNORMAL. Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (↑). Analyst Comment. HY OAS is now 10 bp from the Abnormal line and 35 bp from BIZ-01's 3.75% line. The widening came on the day Treasury yields fell sharply, so the spread move reflects credit risk, not just a rates move.
Kpler's 23 Oct briefing (flows to 21 Oct) puts the 7-day Hormuz clearance at 12,653 kbd, about 74% of the 17,147 kbd pre-war baseline; Red Sea loadings average 5,134 kbd, about 83% above baseline. Kpler Insight reports intensified Iranian attacks on commercial vessels and Houthi attacks on Saudi Arabia, and says Yanbu exports have averaged about 3 mbd since the restart (Kpler, 23 Oct). Brent settled at $116.72, up 3.1% and the highest since April (CNBC, 23 Oct). Wells Fargo estimates Q3 diesel is up about 60% year on year and warns of a growing margin drag at discount retailers (CNBC, 23 Oct). The Drewry WCI is carried at $4,585 (22 Oct); the next print is due 29 Oct. The 30 Oct port strikes in Italy and France are still called (Ports Europe). Indicators. S-1 ABNORMAL (carried). S-2 ABNORMAL (carried). S-3 SIGNIFICANT (↑). S-4 ABNORMAL (carried). S-5 ABNORMAL. Roll-up: 1 Significant + 4 Abnormal = ENVIRONMENT FOR CRISIS (↑). Analyst Comment. Kpler flags its latest week as a preliminary floor that has typically settled 1.5–2 times higher, so S-3 could revert. We score the published figure. Houthi missiles at Yanbu (WIRE World Instability) put the Red Sea bypass, now carrying 83% above its baseline, directly at risk.
USTR has proposed to further suspend its Section 301 action on China's maritime, logistics and shipbuilding sectors through 9 Jan 2027, "to allow for further negotiation with China." Comments are due 30 Oct; the notice publishes on 26 Oct (Federal Register 2026-21755). OFAC's last action remains 21 Oct (OFAC recent actions). No new BIS document was found on the Federal Register public-inspection list. Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: 1 Abnormal = NO CRISIS (=).
The S&P 500 fell 0.52% to 7,623.68, 2.5% below its record; the Dow fell 1.23% to 52,215.16 as American Express said it will cut about 5% of its global workforce (CNBC; AP, 23 Oct). VIX closed at 19.45 after touching 20.66 (Yahoo Finance). FactSet's blended Q3 EPS growth is 29.5%, with 24% of companies reported (FactSet, 23 Oct). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (↑).
Resolved today: - BIZ-05 (SOX ≤ 10,976.04, 23 Oct–20 Nov; 30%): resolved-hit. FRED shows 10,779.46 on 23 Oct. Brier 0.49.
Open: - BIZ-01 (HY OAS ≥ 3.75%): 3.40%, not met. - BIZ-02 (WCI ≤ $4,300 by 12 Nov): $4,585, trending miss. - BIZ-03 (S&P 500 record above 7,818.93): 2.5% short. - BIZ-04 (CCC OAS ≥ 14.00%): 13.40%, not met. - BIZ-06 (Nasdaq ≤ 24,839.81): 25,955.34, not met. - BIZ-07 (WCI ≥ $5,000): next print 29 Oct.
New (dated 2026-10-24; logged in the prediction ledger): - BIZ-08: The VIX (FRED VIXCLS) closes at or above 25.00 on any trading day from 26 Oct to 20 Nov 2026. 35%, unlikely. Resolve by 2026-11-20. - BIZ-09: S&P Global Ratings, Moody's or Fitch announces a downgrade of Oracle's long-term issuer or senior unsecured rating (any notch) from 24 Oct to 31 Dec 2026. 35%, unlikely. Resolve by 2026-12-31.
FRED (NASDAQSOX, BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM); CNBC (23 Oct, two pieces); Reuters via Yahoo Finance (23 Oct); AP (23 Oct); SK hynix Newsroom; Bloomberg (21 Oct); CreditFlow (21 Oct); Stanger; Kpler media briefing (23 Oct); Ports Europe; Federal Register (2026-21755 and public-inspection list); OFAC; Yahoo Finance and WSJ (VIX); FactSet (23 Oct).
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe