WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Sunday, 25 October 2026 | Vol. 2026-298 | As of 250630 EDT OCT 26
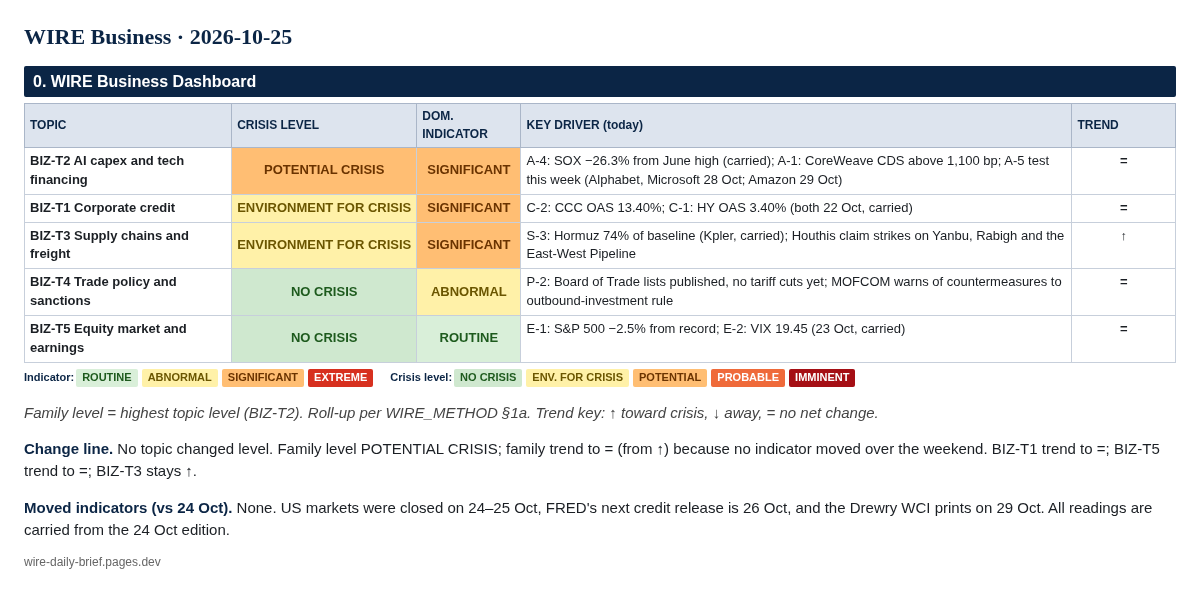
BLUF. WIRE Business holds at POTENTIAL CRISIS (=) over a weekend with no market prints; no indicator changed score. The main new risk is physical: the Houthis said they targeted an Aramco facility in Yanbu, the Rabigh refinery, crude pumping stations and the East-West Pipeline on Saturday, the route that carries Saudi exports around the closed Strait of Hormuz, and Saudi Civil Defence reported missile debris near Rabigh, Jeddah and Taif (Reuters). Damage was not confirmed. The State Department has ordered non-emergency US staff out of Saudi Arabia. Credit data stay at 22 Oct (HY OAS 3.40%, CCC 13.40%; FRED's next release is 26 Oct). The week ahead decides BIZ-T2: Alphabet and Microsoft report capex on 28 Oct, after the Fed's 2:00 PM decision, and Amazon reports on 29 Oct. On trade, USTR has published the US–China Board of Trade product lists, while China's commerce ministry reserved the right to counter a proposed US outbound-investment rule.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX −26.3% from June high (carried); A-1: CoreWeave CDS above 1,100 bp; A-5 test this week (Alphabet, Microsoft 28 Oct; Amazon 29 Oct) | = |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.40%; C-1: HY OAS 3.40% (both 22 Oct, carried) | = |
| BIZ-T3 Supply chains and freight | ENVIRONMENT FOR CRISIS | SIGNIFICANT | S-3: Hormuz 74% of baseline (Kpler, carried); Houthis claim strikes on Yanbu, Rabigh and the East-West Pipeline | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-2: Board of Trade lists published, no tariff cuts yet; MOFCOM warns of countermeasures to outbound-investment rule | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −2.5% from record; E-2: VIX 19.45 (23 Oct, carried) | = |
Family level = highest topic level (BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic changed level. Family level POTENTIAL CRISIS; family trend to = (from ↑) because no indicator moved over the weekend. BIZ-T1 trend to =; BIZ-T5 trend to =; BIZ-T3 stays ↑.
Moved indicators (vs 24 Oct). None. US markets were closed on 24–25 Oct, FRED's next credit release is 26 Oct, and the Drewry WCI prints on 29 Oct. All readings are carried from the 24 Oct edition.
Week ahead. Alphabet and Microsoft report after the close on 28 Oct, and Amazon on 29 Oct. Reuters says investor focus is on capex guidance and returns, with hyperscaler capital spending expected at about $800 billion this year (Reuters via Investing.com). Intel and Sandisk also report on 29 Oct (Reuters via Investing.com). Private credit exposure. Reuters reports CoreWeave has about $50 billion of debt (LSEG data), much of it from private-credit facilities led by Blackstone, Magnetar, Carlyle and BlackRock, and that Carlyle estimates private credit could be called on to finance about $1 trillion of the AI-compute build-out (Reuters via Investing.com, 16 Oct). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT. A-3 ROUTINE (−6.0%, carried). A-4 SIGNIFICANT (−26.3%, carried). A-5 ROUTINE. Roll-up: 3 Significant, no Extreme = POTENTIAL CRISIS (=). Analyst Comment. The two scheduled reports this week can move A-5 directly. One capex cut would add an Abnormal; a cut paired with a pulled financing would put the topic near PROBABLE. We assess a cut as very unlikely (new BIZ-10), because the stress so far is in how the spending is financed, not in the plans themselves.
FRED's latest values are for 22 Oct: HY OAS 3.40%, CCC OAS 13.40%, IG OAS 0.89%; the next release is 26 Oct (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). No new private-credit gate or suspension was found over the weekend. Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL. C-6 ABNORMAL. Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. The 23 Oct spread print, due Monday, will show whether Friday's equity selloff and record Brent pushed HY OAS through the 3.50% Abnormal line (new BIZ-11).
Saudi bypass under fire. Houthi spokesman Yahya Saree said the group targeted King Khalid International Airport in Riyadh, an Aramco facility in Yanbu, the Rabigh refinery, crude pumping stations and the East-West Pipeline on Saturday. The coalition said it destroyed two ballistic missiles fired toward Yanbu and Taif, and Saudi Civil Defence said debris fell in the Mecca and Medina regions, including Jeddah, Taif and Rabigh. Saudi authorities did not say whether any target was hit (Reuters via Business Standard, 25 Oct). On Sunday the coalition said it intercepted a ballistic missile and two drones aimed at Riyadh and ten ballistic missiles fired toward southern Saudi Arabia; Riyadh's airport reopened terminals 1 and 2 (Reuters via Investing.com, 25 Oct; AP, 25 Oct). Operating environment. The State Department ordered non-emergency US government employees and their families to leave Saudi Arabia, citing Houthi attacks (US Embassy travel advisory). Flows. Kpler's latest briefing (flows to 21 Oct) put the 7-day Hormuz clearance at about 74% of baseline and Red Sea loadings 83% above baseline; Kpler also reports Middle East producers cutting prices to win buyers while freight rates stay near records (Kpler, 23 Oct; Kpler blog). The Drewry WCI is carried at $4,585; the 30 Oct Italian and French port strikes are still called. Indicators. S-1 ABNORMAL. S-2 ABNORMAL. S-3 SIGNIFICANT. S-4 ABNORMAL. S-5 ABNORMAL. Roll-up: 1 Significant + 4 Abnormal = ENVIRONMENT FOR CRISIS (↑). Analyst Comment. The trend stays ↑ because the targets have shifted from airports to the export system that replaced Hormuz. A confirmed hit that stops Yanbu loadings or the East-West Pipeline would cut the main bypass and would likely move S-3 to Extreme; until damage is confirmed, nothing is scored on the claims.
USTR published the lists of non-strategic US and Chinese goods eligible for lower tariffs under the Board of Trade's "30-for-30" framework, with no tariff cuts yet (Paral, citing InsideTrade, 24 Oct; MOFCOM). The proposed suspension of the maritime Section 301 action to 9 Jan 2027 publishes on 26 Oct (Federal Register 2026-21755). China's commerce ministry said a US Treasury proposal to widen outbound-investment curbs (adding biotechnology and expanding high-performance computing and hypersonics) was discriminatory, and reserved the right to take countermeasures (Reuters via Investing.com, 24 Oct). OFAC's last program updates remain dated 21 Oct (OFAC). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: 1 Abnormal = NO CRISIS (=). Analyst Comment. The truce is still being implemented, but the countermeasure warning is the first open threat of retaliation since the September round. A named Chinese countermeasure would move P-2 to Abnormal.
No trading over the weekend. Readings carried: S&P 500 7,623.68 (−2.5% from record), VIX 19.45, FactSet Q3 blended EPS +29.5%. Reuters cites LSEG data showing Q3 S&P 500 earnings on pace for growth above 32%, with about a third of the index reporting this week (Reuters via Investing.com, above). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (=).
Resolved today: none.
Open: BIZ-01 (HY OAS ≥ 3.75%; 3.40%), BIZ-02 (WCI ≤ $4,300; $4,585), BIZ-03 (S&P 500 record; 2.5% short), BIZ-04 (CCC OAS ≥ 14.00%; 13.40%), BIZ-06 (Nasdaq ≤ 24,839.81; 25,955.34), BIZ-07 (WCI ≥ $5,000; next print 29 Oct), BIZ-08 (VIX ≥ 25; window opens 26 Oct), BIZ-09 (Oracle downgrade by 31 Dec).
New (dated 2026-10-25; logged in the prediction ledger): - BIZ-10: Alphabet, Microsoft or Amazon lowers its capital-expenditure outlook for calendar 2026 or its next fiscal year below its prior stated guidance in its earnings release or call, 28–30 Oct 2026. 15%, very unlikely. Resolve by 2026-10-31. - BIZ-11: FRED BAMLH0A0HYM2 (HY OAS) shows a daily value at or above 3.50% for any date from 23 Oct to 6 Nov 2026. 50%, roughly even chance. Resolve by 2026-11-09.
FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS); Reuters via Investing.com (16, 24 and 25 Oct; week-ahead pieces); Reuters via Business Standard (25 Oct); AP (25 Oct); US Embassy Riyadh travel advisory; Kpler media briefing (23 Oct) and Kpler blog; Paral/InsideTrade (24 Oct); MOFCOM; Federal Register 2026-21755; OFAC.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe