WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Monday, 26 October 2026 | Vol. 2026-299 | As of 260630 EDT OCT 26
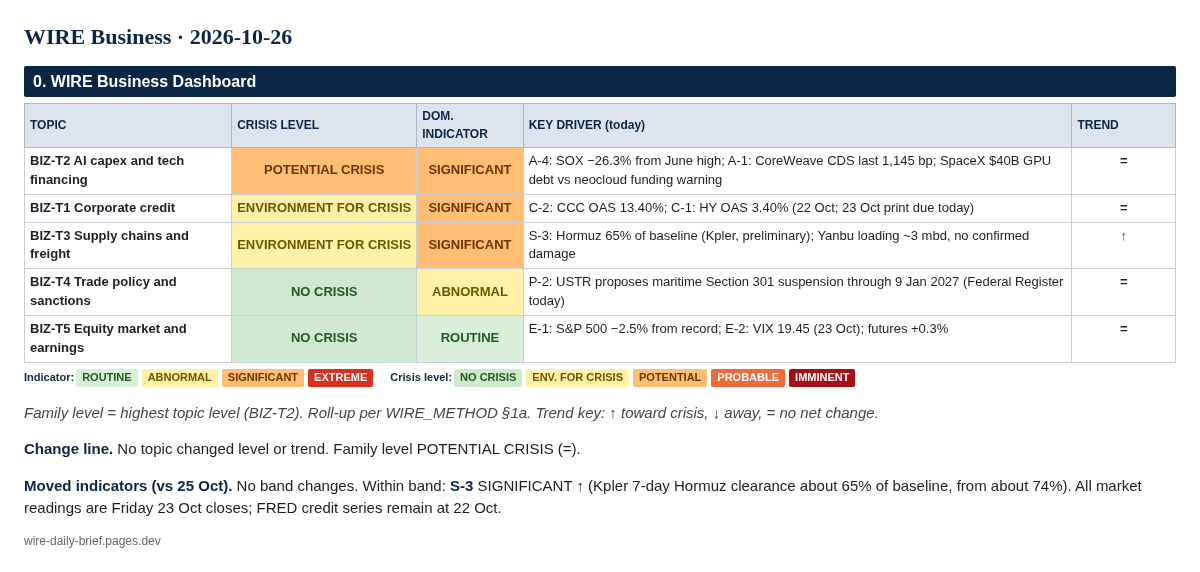
BLUF. WIRE Business holds at POTENTIAL CRISIS (=) going into the busiest week of the quarter; no indicator changed band. Kpler's 26 Oct briefing puts the 7-day Hormuz clearance at about 65% of the pre-war baseline, down from 74%, a preliminary floor that keeps S-3 Significant and the supply-chain trend ↑. Kpler also reports Yanbu exports averaging about 3 mbd since the East-West Pipeline restarted, with no confirmed damage from the Houthi strike claims. In AI financing, SpaceX says it closed $40 billion of debt for GPUs while its chief executive wrote that debt markets have "almost entirely shut off" for firms without revenue outside AI data centers; neocloud shares fell before the open. FRED credit and VIX data still end at 22 Oct (HY OAS 3.40%, CCC 13.40%); the 23 Oct print is due today. US index futures were up about 0.3% before Wednesday's Fed decision and the Alphabet, Microsoft (28 Oct) and Amazon (29 Oct) reports.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX −26.3% from June high; A-1: CoreWeave CDS last 1,145 bp; SpaceX $40B GPU debt vs neocloud funding warning | = |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.40%; C-1: HY OAS 3.40% (22 Oct; 23 Oct print due today) | = |
| BIZ-T3 Supply chains and freight | ENVIRONMENT FOR CRISIS | SIGNIFICANT | S-3: Hormuz 65% of baseline (Kpler, preliminary); Yanbu loading ~3 mbd, no confirmed damage | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-2: USTR proposes maritime Section 301 suspension through 9 Jan 2027 (Federal Register today) | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −2.5% from record; E-2: VIX 19.45 (23 Oct); futures +0.3% | = |
Family level = highest topic level (BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic changed level or trend. Family level POTENTIAL CRISIS (=).
Moved indicators (vs 25 Oct). No band changes. Within band: S-3 SIGNIFICANT ↑ (Kpler 7-day Hormuz clearance about 65% of baseline, from about 74%). All market readings are Friday 23 Oct closes; FRED credit series remain at 22 Oct.
Closes. The Nasdaq Composite closed at 25,955.34 on 23 Oct, 6.0% below its 6 Oct record of 27,599.79, and the S&P 500 and Nasdaq posted a second straight weekly loss (CNBC, 23 Oct; CNBC live, 26 Oct). The SOX closed at 10,779.46 on 23 Oct, 26.3% below its 22 Jun high (FRED NASDAQSOX). Financing split. Elon Musk said SpaceX closed $40 billion of debt financing to buy GPUs, citing its investment-grade status and Starlink and launch revenue, and wrote that debt markets have "almost entirely shut off" for companies without substantial revenue outside AI data centers, predicting a shakeout among "200+ neoclouds" (CNBC, 26 Oct; CNA/Reuters). CoreWeave, Nebius and Iren were down about 2% before the open (TipRanks, 26 Oct). CoreWeave's 5-year CDS last stood at 1,145 bp, and its unsecured debt yields about 15% (CNBC, updated 23 Oct). No new rating action on Oracle was found (BIZ-09 open). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT (carried). A-3 ROUTINE (−6.0%). A-4 SIGNIFICANT (−26.3%). A-5 ROUTINE. Roll-up: 3 Significant, no Extreme = POTENTIAL CRISIS (=). Analyst Comment. The market is splitting AI borrowers by the quality of their cash flow: investment-grade issuers with other revenue can still raise large sums, while pure-play neoclouds pay distress-level spreads. That pattern fits a funding squeeze at the edge, not a system-wide freeze. The week's capex guidance remains the main test; we still judge a hyperscaler capex cut very unlikely (BIZ-10, 15%).
FRED's latest values remain 22 Oct: HY OAS 3.40%, CCC OAS 13.40%, IG OAS 0.89%, with the next release dated 26 Oct (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). Bloomberg reported on 21 Oct that rising yields caused the biggest run of debt-sale delays this year (Bloomberg). Golub's non-traded BDC tender closes on 28 Oct, and several large non-traded BDCs report Q3 tender results around month-end (CrowdfundedWealth tracker, citing SEC filings). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL. C-6 ABNORMAL. Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. Friday's broad equity selloff and record-area Brent make some widening in the 23 Oct print likely; whether HY crosses 3.50% (BIZ-11, 50%) is the first test of contagion from the CCC tail.
Hormuz. Kpler's 26 Oct briefing (flows to 24 Oct) puts the 7-day total Hormuz clearance at 11,213 kbd, about 65% of the 17,147 kbd baseline; tanker crossings were 8 on 24 Oct against a pre-war 50, and Fujairah and Oman loadings ran about 20% above baseline. Kpler says the latest readings are preliminary floors that have typically settled 1.5 to 2 times higher (Kpler media briefing, 26 Oct). Saudi bypass. Kpler reports Yanbu exports averaging about 3 mbd since the East-West Pipeline restarted in late September, Aramco offering spot cargoes from Yanbu and Sidi Kerir, and the 7-day Red Sea volume about 20% below its baseline (same briefing). Saudi air defences intercepted another ballistic missile aimed at Riyadh on Monday and the coalition says it destroyed four Houthi launchers (Arab News, 26 Oct). Freight. Kpler cites the IMO as reporting at least 10 attacks on VLCCs in October; the Mideast Gulf–China VLCC rate fell $2.13 to $35.23/bbl (Kpler). Drewry WCI is carried at $4,585 (22 Oct; next print 29 Oct). The 30 Oct Italian and French port strikes remain called. Indicators. S-1 ABNORMAL. S-2 ABNORMAL. S-3 SIGNIFICANT (↑ within band). S-4 ABNORMAL. S-5 ABNORMAL. Roll-up: 1 Significant + 4 Abnormal = ENVIRONMENT FOR CRISIS (↑). Analyst Comment. The bypass is still working, which is why we keep S-3 short of Extreme even at 65%. The trend stays ↑ because the strait reading fell and the attacks on Saudi targets continue; a confirmed hit on Yanbu or the pipeline remains the trigger for Extreme.
USTR's notice proposing to further suspend the maritime, logistics and shipbuilding Section 301 action for two months, through 9 Jan 2027, to allow further negotiation with China, published today (Federal Register 2026-21755). China's commerce ministry warned the UK of countermeasures if it aligns with EU import curbs on Chinese EVs (SCMP). OFAC's latest listed actions are dated 21 Oct (OFAC recent actions). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: 1 Abnormal = NO CRISIS (=). Analyst Comment. The US is extending, not escalating, the China track; we judge it likely the suspension is finalized before the current one lapses (new BIZ-13).
The S&P 500 closed at 7,623.68 on 23 Oct (−0.5% on the day and week; 2.5% below its 7,818.93 record); the Dow fell 1.2% (CNBC, 23 Oct). VIX closed at 19.45 on 23 Oct (Yahoo Finance; FRED VIXCLS last 19.03 on 22 Oct). Before Monday's open, S&P 500 futures were up 0.3%, and fed funds futures implied about a 90% chance of a hold on Wednesday (CNBC live, 26 Oct). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (=).
Resolved today: none. No BIZ row is due; BIZ-11 awaits the 23 Oct FRED print and BIZ-10's window opens 28 Oct.
Open: BIZ-01 (HY OAS ≥ 3.75%; 3.40%), BIZ-02 (WCI ≤ $4,300; $4,585), BIZ-03 (S&P 500 record; 2.5% short), BIZ-04 (CCC OAS ≥ 14.00%; 13.40%), BIZ-06 (Nasdaq ≤ 24,839.81; 25,955.34), BIZ-07 (WCI ≥ $5,000), BIZ-08 (VIX ≥ 25; window open), BIZ-09 (Oracle downgrade by 31 Dec), BIZ-10 (hyperscaler capex cut, 28–30 Oct), BIZ-11 (HY OAS ≥ 3.50% by 6 Nov).
New (dated 2026-10-26; logged in the prediction ledger): - BIZ-12: CoreWeave's 5-year CDS is reported above its 15 Oct intraday record of 1,194.5 bp on any day from 26 Oct to 20 Nov 2026. 35%, unlikely. Resolve by 2026-11-23. - BIZ-13: USTR finalizes the further suspension of the maritime Section 301 action through 9 Jan 2027 (Federal Register notice or USTR release) dated 26 Oct to 10 Nov 2026. 80%, likely. Resolve by 2026-11-11.
FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS, NASDAQSOX); CNBC (23 and 26 Oct; CoreWeave 21/23 Oct; SpaceX 26 Oct); CNA/Reuters; TipRanks; Bloomberg (21 Oct); CrowdfundedWealth (SEC filings); Kpler media briefing (26 Oct); Arab News (26 Oct); Federal Register 2026-21755; SCMP; OFAC; Yahoo Finance.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe