WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Tuesday, 27 October 2026 | Vol. 2026-300 | As of 270700 EDT OCT 26
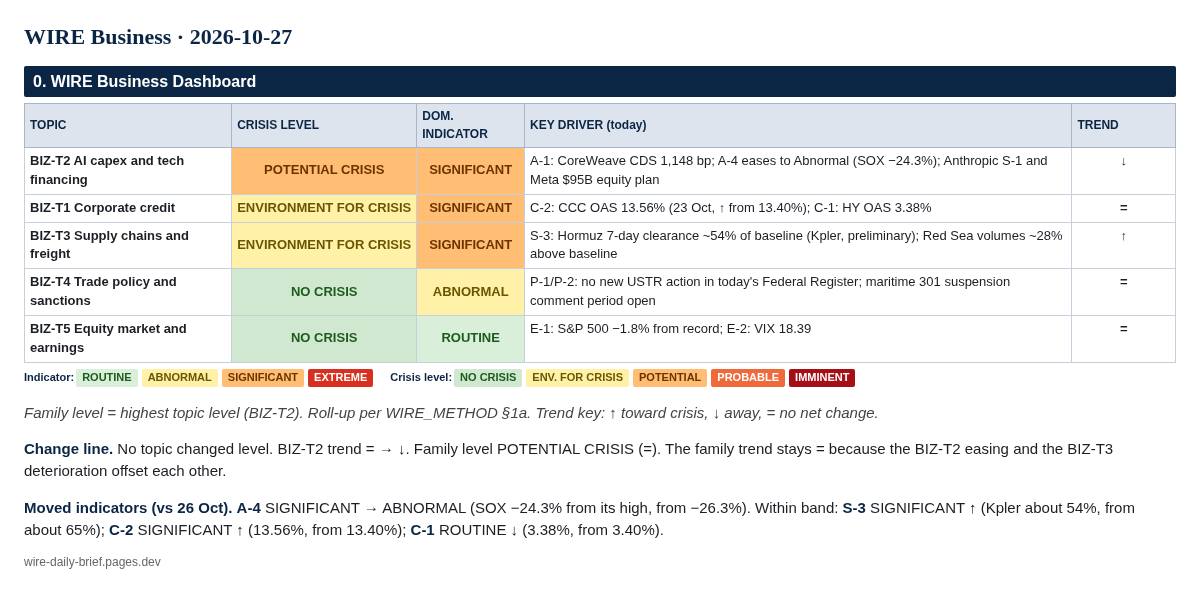
BLUF. WIRE Business holds at POTENTIAL CRISIS (=), with the two main pressures moving in opposite directions. In AI financing, Anthropic publicly filed its S-1 for a Nasdaq listing on Monday, and Meta announced plans to raise $95 billion in equity for AI infrastructure. Chip stocks rallied: the SOX closed at 11,083.47, 24.3% below its June high, which moves A-4 down from Significant to Abnormal and sets the BIZ-T2 trend to ↓. CoreWeave's 5-year CDS still traded at 1,148 bp (S&P Global MI), so A-1 stays Significant. In supply chains, Kpler's 27 Oct briefing puts the 7-day Hormuz clearance at about 54% of the pre-war baseline (down from 65%). That is a preliminary floor, but it keeps S-3 Significant and the BIZ-T3 trend ↑. FRED's 23 Oct credit print shows CCC OAS widening to 13.56% while HY eased to 3.38%. No BIZ call resolved today.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-1: CoreWeave CDS 1,148 bp; A-4 eases to Abnormal (SOX −24.3%); Anthropic S-1 and Meta $95B equity plan | ↓ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.56% (23 Oct, ↑ from 13.40%); C-1: HY OAS 3.38% | = |
| BIZ-T3 Supply chains and freight | ENVIRONMENT FOR CRISIS | SIGNIFICANT | S-3: Hormuz 7-day clearance ~54% of baseline (Kpler, preliminary); Red Sea volumes ~28% above baseline | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1/P-2: no new USTR action in today's Federal Register; maritime 301 suspension comment period open | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −1.8% from record; E-2: VIX 18.39 | = |
Family level = highest topic level (BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic changed level. BIZ-T2 trend = → ↓. Family level POTENTIAL CRISIS (=). The family trend stays = because the BIZ-T2 easing and the BIZ-T3 deterioration offset each other.
Moved indicators (vs 26 Oct). A-4 SIGNIFICANT → ABNORMAL (SOX −24.3% from its high, from −26.3%). Within band: S-3 SIGNIFICANT ↑ (Kpler about 54%, from about 65%); C-2 SIGNIFICANT ↑ (13.56%, from 13.40%); C-1 ROUTINE ↓ (3.38%, from 3.40%).
Listings and raises. Anthropic, PBC filed a Form S-1 on 26 Oct (accepted 09:00 ET) for a Class A listing on the Nasdaq Global Select Market under "ANT"; the share count and price range are not yet set (SEC EDGAR; Anthropic release). Meta said on 26 Oct it would raise $35 billion through underwritten public equity offerings and a further $60 billion through an at-the-market program for AI infrastructure. Nvidia said on 27 Oct it will invest $3 billion in the offering (CNBC, 27 Oct; NVIDIA Newsroom). Closes and credit. Semiconductor stocks rallied on the filing (CNBC live, 26 Oct). The SOX closed at 11,083.47 on 26 Oct (FRED NASDAQSOX), and the Nasdaq Composite at 26,169.38 (+0.82%), 5.2% below its 6 Oct record. CoreWeave's 5-year CDS traded at 1,148 bp on Monday morning, after peaking at 1,167 bp on 22 Oct in S&P Global Market Intelligence's 12-month data (Benzinga, 26 Oct, citing S&P Global MI). CoreWeave bonds gained 1/2 to 1 point on Monday (CreditFlow HY close, below). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT (carried; the 30-day count of pulled listings stands, and the Anthropic filing is a new listing, not a pulled one). A-3 ROUTINE (−5.2%). A-4 ABNORMAL (−24.3%, ↓ from Significant). A-5 ROUTINE (Meta is adding funding, not cutting capex). Roll-up: 2 Significant + 1 Abnormal = POTENTIAL CRISIS (↓). Analyst Comment. Two of the largest AI names are raising money in public markets in the same week. That cuts against a funding freeze at the top of the stack. The weak point is still the pure-play neocloud tier, where CDS pricing implies distress. The SOX is only 0.7 points inside the Abnormal band, so one bad session would undo the move. The hyperscaler reports on 28–29 Oct remain the test (BIZ-10, 15%).
FRED's 23 Oct values: HY OAS 3.38% (22 Oct 3.40%), CCC OAS 13.56% (13.40%), IG OAS 0.91% (0.89%); the next release is due today (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). Bloomberg reported that CCC spreads hit a four-year high last week and that the CCC–BB gap is the widest since the pandemic (The Star/Bloomberg, 26 Oct). The US HY primary market added three deals on 26 Oct but priced none. October volume to date is $10.2 billion, 25% below last October, and $3.1 billion is scheduled for this week (CreditFlow HY close, 26 Oct). Q3 NAV-BDC redemption requests were 11.5% of tender NAV, down from 12.7%, with about 40% fulfilled (Stanger). Golub's GCRED tender closes 28 Oct (CrowdfundedWealth). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT (↑ within band). C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL. C-6 ABNORMAL. Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. Stress is still concentrated in the CCC tail. The broad HY index eased on the same day, and the primary market is slow but open. BIZ-04 (CCC ≥ 14.00%) is 44 bp away.
Hormuz. Kpler's 27 Oct briefing (flows to 25 Oct) puts the 7-day total Hormuz clearance at 9,337 kbd, about 54% of the 17,147 kbd baseline. Strait transits alone, excluding Iranian-origin cargoes, averaged 8,300 kbd, "just under half" of baseline. Tanker crossings were 6 on 25 Oct and averaged 13 over the week, against a pre-war 50. Kpler says these preliminary readings have typically settled 1.5 to 2 times higher. Kpler Insight "sees Iran leaning towards escalation" before the 3 Nov US midterms (Kpler media briefing, 27 Oct). Bypass. Fujairah and Oman loadings averaged 4,289 kbd, about 26% above baseline. Red Sea volumes averaged 3,575 kbd, about 28% above baseline, and Yanbu has averaged about 3 mbd since the pipeline restart. Non-Iranian Middle East crude supply averaged 16.7 mbd in October, against 16.3 mbd before the war (same briefing). Aramco told staff to evacuate its Dhahran headquarters on 22 Oct as Houthi attacks intensified (Reuters via Investing.com). Freight and labor. Kpler cites at least 10 attacks on VLCCs in October and says war risk, not vessel supply, drives tanker rates. Drewry WCI is carried at $4,585 (22 Oct; next print 29 Oct). The 30 Oct strikes remain called: eight Italian ports (Ports Europe), and French unions expect most ports to stop (Europe 1). Indicators. S-1 ABNORMAL. S-2 ABNORMAL (carried). S-3 SIGNIFICANT (↑ within band; 46% below baseline against the 50% Extreme line). S-4 ABNORMAL. S-5 ABNORMAL. Roll-up: 1 Significant + 4 Abnormal = ENVIRONMENT FOR CRISIS (↑). Analyst Comment. Total supply is holding because the bypass routes run above baseline. That is why we score this a flow-and-cost problem rather than a shortage, and why S-3 stays short of Extreme. A confirmed 7-day reading below 50%, or confirmed damage at Yanbu, would change that (new BIZ-15).
Today's Federal Register carries no new USTR tariff action (FR issue, 27 Oct). The proposal to suspend the maritime Section 301 action through 9 Jan 2027 is still open for comment (FR 2026-21755). OFAC's only action on 26 Oct was amended FAQs on blocking and reject reports; its last designations were on 21 Oct (OFAC recent actions). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: 1 Abnormal = NO CRISIS (=).
The S&P 500 closed at 7,676.77 on 26 Oct (+0.70%), 1.8% below its 7,818.93 record. The Dow rose 0.28% to 52,361.58 (CNBC live, 26 Oct). VIX closed at 18.39 (Yahoo Finance ^VIX; FRED VIXCLS last 19.45, 23 Oct). Index futures were up about 0.1% before the open, with the Fed's two-day meeting starting today (TipRanks, 27 Oct). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (=).
Resolved today: none. No BIZ row is due. BIZ-12 is not met: the highest level seen since 26 Oct is 1,148 bp, against the 1,194.5 bp line. BIZ-11 is still open on the 23 Oct print (3.38%).
Open: BIZ-01 (HY ≥ 3.75%; 3.38%), BIZ-02 (WCI ≤ $4,300; $4,585), BIZ-03 (S&P record; 1.8% short), BIZ-04 (CCC ≥ 14.00%; 13.56%), BIZ-06 (Nasdaq ≤ 24,839.81; 26,169.38), BIZ-07 (WCI ≥ $5,000), BIZ-08 (VIX ≥ 25; 18.39), BIZ-09 (Oracle downgrade), BIZ-10 (hyperscaler capex cut, 28–30 Oct), BIZ-11 (HY ≥ 3.50% by 6 Nov), BIZ-12 (CoreWeave CDS > 1,194.5 bp), BIZ-13 (USTR finalizes 301 suspension).
New (dated 2026-10-27; logged in the prediction ledger): - BIZ-14: Anthropic's Class A shares begin trading on Nasdaq (ticker ANT) on or before 31 Dec 2026. 65%, likely. Resolve by 2027-01-04. - BIZ-15: A Kpler media briefing dated 28 Oct to 13 Nov 2026 reports a 7-day average total Hormuz clearance at or below 50% of the pre-war baseline (≤ 8,574 kbd). 40%, unlikely. Resolve by 2026-11-16.
SEC EDGAR (Anthropic S-1); Anthropic; CNBC (26–27 Oct); NVIDIA Newsroom; FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS, NASDAQSOX); Benzinga/S&P Global MI; The Star/Bloomberg; CreditFlow; Stanger; CrowdfundedWealth; Kpler media briefing (27 Oct); Reuters via Investing.com; Ports Europe; Europe 1; Federal Register; OFAC; Yahoo Finance; TipRanks.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe