WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Wednesday, 28 October 2026 | Vol. 2026-301 | As of 280700 EDT OCT 26
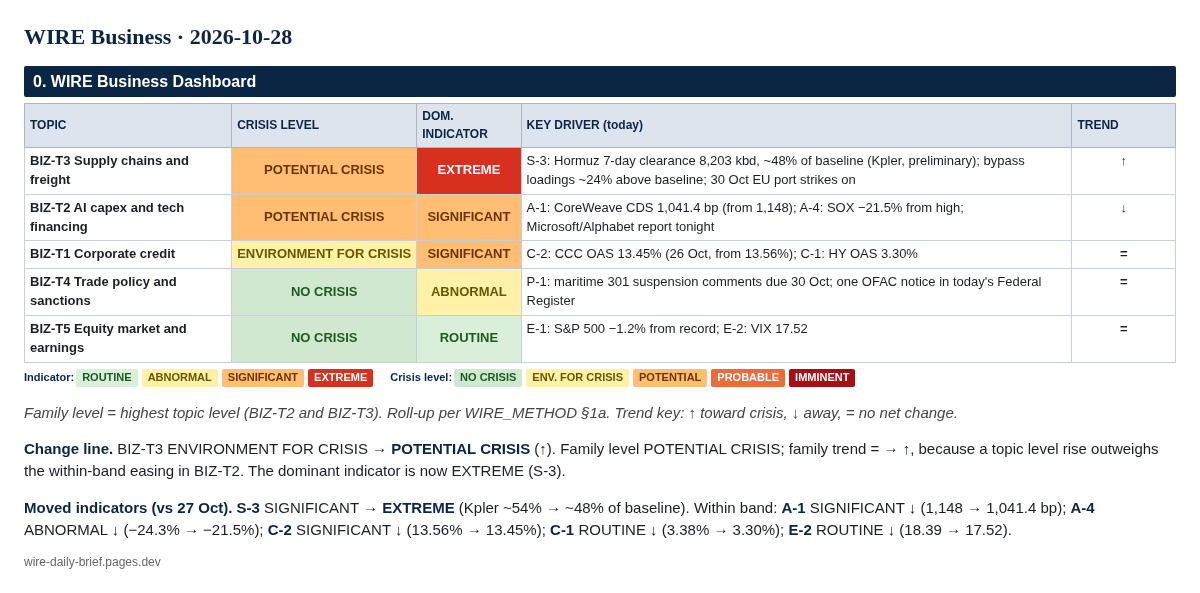
BLUF. WIRE Business holds at POTENTIAL CRISIS but turns ↑, because supply chains now carry the family's first Extreme reading. Kpler's 28 Oct briefing puts the 7-day Hormuz clearance at 8,203 kbd, about 48% of the pre-war baseline, past the "over 50% below" Extreme line. That moves S-3 to Extreme and BIZ-T3 up to POTENTIAL CRISIS. The reading is a preliminary floor, and bypass routes are still running above baseline. The Wall Street Journal reports that the US told Gulf states to prepare for a short, intense campaign against Iran after the 3 Nov midterms. AI financing eased again: CoreWeave's 5-year CDS fell to 1,041 bp, and the SOX closed 21.5% below its June high. FRED's 26 Oct credit print tightened (HY 3.30%, CCC 13.45%). BIZ-15 resolved a hit. Microsoft and Alphabet report after today's close, after the Fed decision at 2 PM ET.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | EXTREME | S-3: Hormuz 7-day clearance 8,203 kbd, ~48% of baseline (Kpler, preliminary); bypass loadings ~24% above baseline; 30 Oct EU port strikes on | ↑ |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-1: CoreWeave CDS 1,041.4 bp (from 1,148); A-4: SOX −21.5% from high; Microsoft/Alphabet report tonight | ↓ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.45% (26 Oct, from 13.56%); C-1: HY OAS 3.30% | = |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1: maritime 301 suspension comments due 30 Oct; one OFAC notice in today's Federal Register | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −1.2% from record; E-2: VIX 17.52 | = |
Family level = highest topic level (BIZ-T2 and BIZ-T3). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. BIZ-T3 ENVIRONMENT FOR CRISIS → POTENTIAL CRISIS (↑). Family level POTENTIAL CRISIS; family trend = → ↑, because a topic level rise outweighs the within-band easing in BIZ-T2. The dominant indicator is now EXTREME (S-3).
Moved indicators (vs 27 Oct). S-3 SIGNIFICANT → EXTREME (Kpler ~54% → ~48% of baseline). Within band: A-1 SIGNIFICANT ↓ (1,148 → 1,041.4 bp); A-4 ABNORMAL ↓ (−24.3% → −21.5%); C-2 SIGNIFICANT ↓ (13.56% → 13.45%); C-1 ROUTINE ↓ (3.38% → 3.30%); E-2 ROUTINE ↓ (18.39 → 17.52).
Hormuz. Kpler's briefing prepared 28 Oct (flows to 26 Oct) puts the 7-day average Total Hormuz Clearance at 8,203 kbd, about 48% of the 17,147 kbd baseline. Strait transits alone, excluding Iranian-origin cargoes, averaged 7,871 kbd (about 46%). Tanker crossings were 8 on 26 Oct and averaged 12 over the week, against a pre-war 50. Kpler says preliminary readings have typically settled 1.5 to 2 times higher. It also cites the IMO as reporting at least 10 attacks on VLCCs in October, and says Tehran's incentive to escalate is "sharpening" before the midterms (Kpler media briefing, 28 Oct). Bypass. In the same briefing, Fujairah and Oman terminal loadings averaged 4,243 kbd, about 24% above baseline, and Red Sea volumes averaged 3,234 kbd, about 15% above baseline. Yanbu exports have averaged about 3 mbd since the East-West Pipeline restarted on 22 Sep. Clearance plus Gulf of Oman loadings averaged 16.3 mbd over 1–26 Oct. Kpler says freight, not a shortage of cargo, keeps delivered crude costs high; the Mideast Gulf–China VLCC rate fell $2.13 to $35.23/bbl. Forward risk. The WSJ reported on 27 Oct that the US told several Gulf Arab states, through diplomatic and military channels, to prepare for a "short, intense military campaign" after the midterms. It also reported that the President has not decided (WSJ; Anadolu, 28 Oct). The White House declined to comment on "sensitive military plans that may or may not exist." Ports. Italy's 24-hour port-sector strike on 30 Oct shows no revocation in the transport ministry's data as of 27 Oct, 22:09 (ScioperiItalia, MIT data). France's CGT ports federation said 24 ports will stop for 24 hours that day (Forwarder News, 26 Oct). Drewry WCI is carried at $4,585 (22 Oct); the next print is due 29 Oct. Indicators. S-1 ABNORMAL (carried). S-2 ABNORMAL (carried). S-3 EXTREME (~52% below baseline; W-1 Extreme line is "flows over 50% below"). S-4 ABNORMAL. S-5 ABNORMAL (strike notice; the strike lasts under 7 days and has not started). Roll-up: 1 Extreme, no other indicator above Abnormal = POTENTIAL CRISIS (↑). No override. Analyst Comment. We score the published figure, as on earlier days, even though it is a preliminary floor that could revise back above 50%. This is still a flow-and-cost shock, not a shortage: the bypass routes are carrying more than their baseline, and total regional supply is close to pre-war. The WSJ report matters because it gives the risk a date. If a post-midterm campaign hits export infrastructure or the bypass terminals (Yanbu, Fujairah), it would likely push S-3 deeper and lift S-1 and S-4 together. That would take BIZ-T3 to PROBABLE.
CoreWeave's 5-year CDS narrowed to 1,041.4 bp on 27 Oct, its lowest in more than a week, citing Markit data (CryptoBriefing, 27 Oct; TokenPost). S&P Global MI data show Nvidia's 5-year CDS at 127 bp on 27 Oct, up from 39 at end-2025 (Benzinga, 27 Oct). The SOX closed at 11,482.51 on 27 Oct, 21.5% below its 14,634.72 high of 22 Jun (FRED NASDAQSOX). The Nasdaq Composite closed at 26,477.81 (+1.18%), 4.1% below its record (Reuters via Yahoo Finance). Nasdaq futures rose before the open after SK hynix's results. Microsoft and Alphabet report after today's close (Reuters via MarketScreener, 28 Oct). Alphabet's last 2026 capex guide was $195–205 billion (Reuters, 22 Jul). Indicators. A-1 SIGNIFICANT (↓ within band). A-2 SIGNIFICANT (carried; the 30-day count of pulled listings stands). A-3 ROUTINE (−4.1%). A-4 ABNORMAL (↓ within band). A-5 ROUTINE. Roll-up: 2 Significant + 1 Abnormal = POTENTIAL CRISIS (↓). Analyst Comment. CoreWeave's CDS is now about 40 bp above the 1,000 bp Significant line. A drop below it would leave A-2 as the only Significant indicator and take BIZ-T2 down to ENVIRONMENT FOR CRISIS. Tonight's hyperscaler reports are the next test (BIZ-10 cut, 15%; new BIZ-17 Alphabet raise, 55%).
FRED's 26 Oct values: HY OAS 3.30% (23 Oct 3.38%), CCC OAS 13.45% (13.56%), IG OAS 0.90% (0.91%) (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). On 26 Oct, ZF North America brought a $500 million 5-year deal (talk in the high 8s) for pricing on 27 Oct (CreditFlow HY midday, 26 Oct). The prior week priced four US deals for $3.385 billion, and Crescent Energy dropped a $1 billion unsecured bond plan (CreditFlow HY close, 23 Oct). Main Street Capital, a BDC, priced $500 million of 6.55% notes due 2030 on 27 Oct (PR Newswire). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT (↓ within band). C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL (carried; the market is open but thin). C-6 ABNORMAL (carried). Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. The CCC tail eased with the broad market. BIZ-04 (CCC ≥ 14.00%) is now 55 bp away, and BIZ-11 (HY ≥ 3.50%) is 20 bp away.
Today's Federal Register carries no USTR or BIS document. Its only OFAC item is a sanctions-action notice (FR API, 28 Oct). On 27 Oct, OFAC posted a settlement with Extreme Networks; its last designations were on 21 Oct (OFAC recent actions). Comments on the proposed further suspension of the maritime Section 301 action through 9 Jan 2027 are due 30 Oct (FR 2026-21755). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: NO CRISIS (=).
The S&P 500 closed at 7,722.60 on 27 Oct (+0.60%), 1.2% below its 7,818.93 record. Technology led and energy lagged as crude eased (Reuters via Yahoo Finance, above). VIX closed at 17.52 (ad-hoc-news, 27 Oct; FRED VIXCLS last 18.39 on 26 Oct, VIXCLS). The FOMC decision is due at 2 PM ET (MarketScreener, above). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (=).
Resolved today: BIZ-15 HIT. Kpler's 28 Oct briefing reports a 7-day Total Hormuz Clearance of 8,203 kbd, below the 8,574 kbd (50%) line. It was called at 40%, so Brier = 0.36. No other BIZ row is due. BIZ-10 (hyperscaler capex cut) resolves after the 28–30 Oct reports.
Open: BIZ-01 (HY ≥ 3.75%; 3.30%), BIZ-02 (WCI ≤ $4,300), BIZ-03 (S&P record; 1.2% short), BIZ-04 (CCC ≥ 14.00%; 13.45%), BIZ-06 (Nasdaq ≤ 24,839.81), BIZ-07 (WCI ≥ $5,000), BIZ-08 (VIX ≥ 25; 17.52), BIZ-09 (Oracle downgrade), BIZ-10, BIZ-11 (HY ≥ 3.50%), BIZ-12 (CoreWeave CDS > 1,194.5 bp; 1,041.4), BIZ-13 (USTR finalizes 301 suspension), BIZ-14 (Anthropic lists by 31 Dec).
New (dated 2026-10-28; logged in the prediction ledger): - BIZ-16: A Kpler media briefing dated 29 Oct to 13 Nov 2026 reports a 7-day average Total Hormuz Clearance at or below 40% of baseline (≤ 6,859 kbd). 30%, unlikely. Resolve by 2026-11-16. - BIZ-17: Alphabet's Q3 results (28–30 Oct) give a 2026 capex outlook with a midpoint above $200 billion, raising the $195–205 billion range. 55%, likely. Resolve by 2026-11-02.
Kpler media briefing (28 Oct); WSJ; Anadolu; ScioperiItalia/MIT; Forwarder News; CryptoBriefing; TokenPost; Benzinga/S&P Global MI; FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS, NASDAQSOX); Reuters via Yahoo Finance and MarketScreener; Reuters (22 Jul); CreditFlow; PR Newswire; Federal Register; OFAC; ad-hoc-news.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe