WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Thursday, 29 October 2026 | Vol. 2026-302 | As of 290630 EDT OCT 26
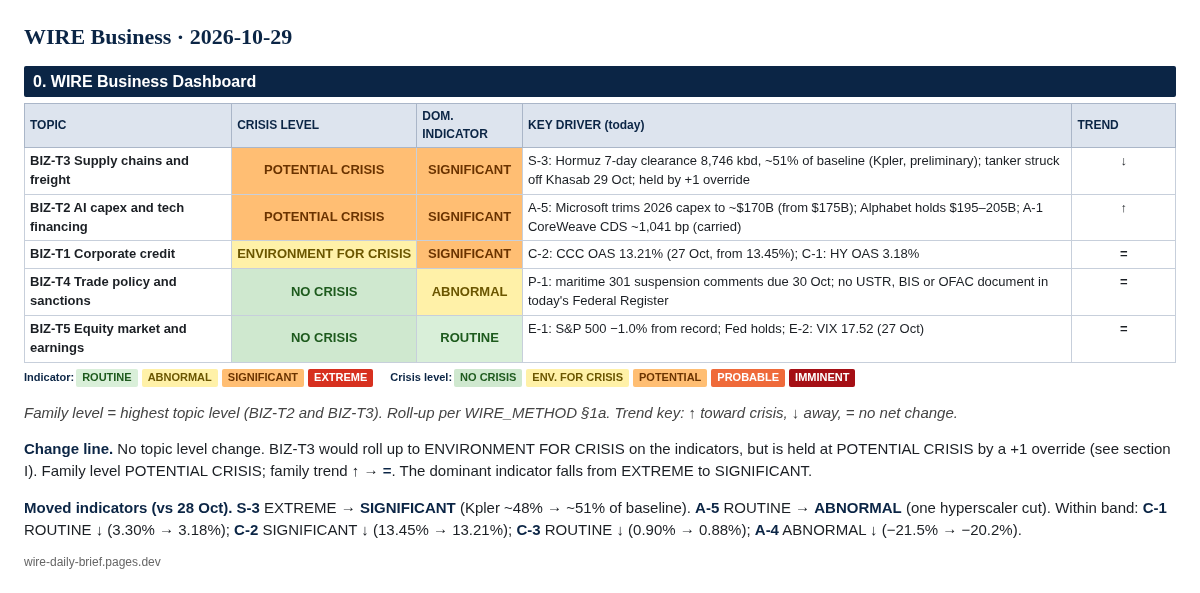
BLUF. WIRE Business holds at POTENTIAL CRISIS with no net change (=): one indicator rose and one fell. Microsoft cut its calendar-2026 capex outlook to about $170 billion from $175 billion, citing delayed third-party GPU capacity. That is the first hyperscaler cut of the cycle and moves A-5 to Abnormal; BIZ-10 resolved a hit. Alphabet held its $195–205 billion range, so BIZ-17 resolved a miss. Kpler's 29 Oct briefing puts the 7-day Hormuz clearance at 8,746 kbd, about 51% of baseline, so S-3 drops back to Significant. We hold BIZ-T3 at POTENTIAL CRISIS by override: a tanker was struck and left burning and mostly submerged 9 nm north of Khasab at 03:00 UTC today, after Kpler's data cutoff. Credit kept easing (HY 3.18%, CCC 13.21%). The Fed held at 3.75–4.00% with two dissents for a hike.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | SIGNIFICANT | S-3: Hormuz 7-day clearance 8,746 kbd, ~51% of baseline (Kpler, preliminary); tanker struck off Khasab 29 Oct; held by +1 override | ↓ |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-5: Microsoft trims 2026 capex to ~$170B (from $175B); Alphabet holds $195–205B; A-1 CoreWeave CDS ~1,041 bp (carried) | ↑ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.21% (27 Oct, from 13.45%); C-1: HY OAS 3.18% | = |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1: maritime 301 suspension comments due 30 Oct; no USTR, BIS or OFAC document in today's Federal Register | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 −1.0% from record; Fed holds; E-2: VIX 17.52 (27 Oct) | = |
Family level = highest topic level (BIZ-T2 and BIZ-T3). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic level change. BIZ-T3 would roll up to ENVIRONMENT FOR CRISIS on the indicators, but is held at POTENTIAL CRISIS by a +1 override (see section I). Family level POTENTIAL CRISIS; family trend ↑ → =. The dominant indicator falls from EXTREME to SIGNIFICANT.
Moved indicators (vs 28 Oct). S-3 EXTREME → SIGNIFICANT (Kpler ~48% → ~51% of baseline). A-5 ROUTINE → ABNORMAL (one hyperscaler cut). Within band: C-1 ROUTINE ↓ (3.30% → 3.18%); C-2 SIGNIFICANT ↓ (13.45% → 13.21%); C-3 ROUTINE ↓ (0.90% → 0.88%); A-4 ABNORMAL ↓ (−21.5% → −20.2%).
Hormuz. Kpler's briefing prepared 29 Oct (flows to 27 Oct) puts the 7-day average Total Hormuz Clearance at 8,746 kbd, about 51% of the 17,147 kbd baseline. Daily readings ranged from 257 kbd on 26 Oct to 5,446 kbd on 27 Oct. Strait transits alone, excluding Iranian-origin cargoes, averaged 7,713 kbd (about 45%), and tanker crossings averaged 12 a day against a pre-war 50. Kpler again says preliminary readings have typically settled 1.5 to 2 times higher (Kpler media briefing, 29 Oct). Bypass. Fujairah and Oman terminal loadings averaged 4,465 kbd, about 31% above baseline. Red Sea volumes averaged 2,396 kbd, about 15% below baseline, a swing from +15% in the 28 Oct briefing. Kpler says war risk, not vessel availability, keeps tanker freight high (same briefing). Attack. UKMTO and Vanguard Tech report that a tanker was struck by an unknown projectile 9 nm north of Khasab, in the southern corridor of the strait, at 03:00 UTC on 29 Oct. The master of a passing Panama-flagged tanker reported it on fire and mostly submerged; the crew's status is unknown. Seatrade cites IMO figures of 34 confirmed attacks on vessels from 28 Sep to 27 Oct (Seatrade Maritime, 29 Oct; CGTN, UKMTO notice). Freight and ports. Drewry WCI is carried at $4,585 (22 Oct); today's print was not out at writing (Drewry WCI). The Italian and French port strikes are set for 30 Oct (28 Oct edition). Indicators. S-1 ABNORMAL (carried). S-2 ABNORMAL (carried). S-3 SIGNIFICANT (~49% below baseline, just inside the Significant band). S-4 ABNORMAL. S-5 ABNORMAL. Roll-up: 1 Significant + 4 Abnormal = ENVIRONMENT FOR CRISIS. Override +1 to POTENTIAL CRISIS: the reading sits one point from the Extreme line on preliminary data that ends 27 Oct, before today's strike in the protected southern corridor. Trend ↓ (indicator eased). Analyst Comment. We do not want the level to whipsaw on a preliminary floor that sits right at the line. Today's attack is a single event and is not itself scored. If it is confirmed as a sinking and the corridor's transit counts fall in the next two briefings, S-3 likely returns to Extreme. If clearance holds above 50% through 3 Nov with no further hits, the override should lapse.
Microsoft. Fiscal Q1 capex was $45.2 billion, because "some third-party capacity deliveries we expected in Q1 were delayed." The CFO guided fiscal Q2 capex above $50 billion and said "for the calendar year, spend should be approximately $170 billion due to the 3P capacity delays" (earnings call transcript). Business Insider reports the previous calendar-2026 forecast as $175 billion (Business Insider, 28 Oct). Azure revenue rose 48%, and the shares rose about 3% after hours (same). Alphabet. Q3 purchases of property and equipment were $51.4 billion, and free cash flow was −$9.1 billion (Alphabet Q3 release, SEC). The CFO said the 2026 range of $195–205 billion "remain[s] unchanged" and capex will "increase significantly in 2027" (transcript; CNBC, 28 Oct). Investing.com reports a roughly 10% after-hours drop on a profit miss (Investing.com). Markets and credit. The SOX closed at 11,684.00 on 28 Oct (+1.75%), 20.2% below its 14,634.72 high (Nasdaq index history). The Nasdaq Composite closed at 26,549.85, 3.8% below its record (CNBC, 28 Oct). No new CoreWeave CDS print was found; A-1 is carried at 1,041.4 bp. Axios reports that bonds tied to CoreWeave-leased data centers still carry a "chunky risk premium" (Axios, 28 Oct). Indicators. A-1 SIGNIFICANT (carried). A-2 SIGNIFICANT (carried). A-3 ROUTINE. A-4 ABNORMAL (↓ within band). A-5 ABNORMAL (1 cut). Roll-up: 2 Significant + 2 Abnormal = POTENTIAL CRISIS (↑). Analyst Comment. Microsoft's cut is about timing: the delayed capacity comes from GPU-as-a-service suppliers, and it guided spending to accelerate in its fiscal second half. The cut is still a signal for BIZ-T2, because the delays point back at the debt-funded neocloud layer this topic watches. Amazon reports after today's close, which closes the BIZ-10 window.
FRED's 27 Oct values: HY OAS 3.18% (26 Oct 3.30%), CCC OAS 13.21% (13.45%), IG OAS 0.88% (0.90%) (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). The Fed held its target range at 3.75–4.00% on 28 Oct in a 10–2 vote, with two dissents for a hike. The 10-year Treasury yield rose 5.2 bp to 5.044% (MarketWatch, 28 Oct). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT (↓ within band). C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL (carried). C-6 ABNORMAL (carried). Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. Spreads are tightening, but a 10-year yield above 5% and an open hike debate raise refinancing costs for the CCC tail. BIZ-04 (CCC ≥ 14.00%) is now 79 bp away and BIZ-11 (HY ≥ 3.50%) 32 bp away.
Today's Federal Register carries no USTR, BIS or OFAC document (FR API, 29 Oct). Comments on the further suspension of the maritime Section 301 action are due 30 Oct (FR 2026-21755). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: NO CRISIS (=).
The S&P 500 closed at 7,743.98 on 28 Oct (+0.28%), its third straight gain and 1.0% below its 7,818.93 record (CNBC and MarketWatch, above). FRED's latest VIX close is 17.52 (27 Oct) (VIXCLS). Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (=).
Resolved today: - BIZ-10 HIT. Microsoft's 28 Oct call set calendar-2026 capex at about $170 billion, below its previous $175 billion forecast. It was called at 15%, so Brier = 0.7225. - BIZ-17 MISS. Alphabet kept its 2026 range at $195–205 billion (midpoint $200 billion, not above it). It was called at 55%, so Brier = 0.3025.
Still open, with no resolution today: BIZ-16 (Kpler ≤ 40%; 29 Oct reading 51%). Others open: BIZ-01, -02, -03 (S&P 1.0% short of its record), -04, -06, -07, -08, -09, -11, -12, -13, -14.
New (dated 2026-10-29; logged in the prediction ledger): - BIZ-18: A Kpler media briefing dated 30 Oct to 13 Nov 2026 again reports a 7-day average Total Hormuz Clearance at or below 50% of baseline (≤ 8,574 kbd). 65%, likely. Resolve by 2026-11-16. - BIZ-19: CoreWeave's 5-year CDS is reported below 1,000 bp on any day from 29 Oct to 20 Nov 2026 (A-1 drops to Abnormal). 40%, unlikely to roughly even. Resolve by 2026-11-23.
Kpler media briefing (29 Oct); Seatrade Maritime; CGTN (UKMTO); Drewry; Microsoft call transcript (StockAnalysis); Business Insider; Alphabet Q3 release (SEC EDGAR); Alphabet call transcript; CNBC; Investing.com; Nasdaq index history; Axios; FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS); MarketWatch; Federal Register.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe