WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Sunday, 1 November 2026 | Vol. 2026-305 | As of 010630 EST NOV 26
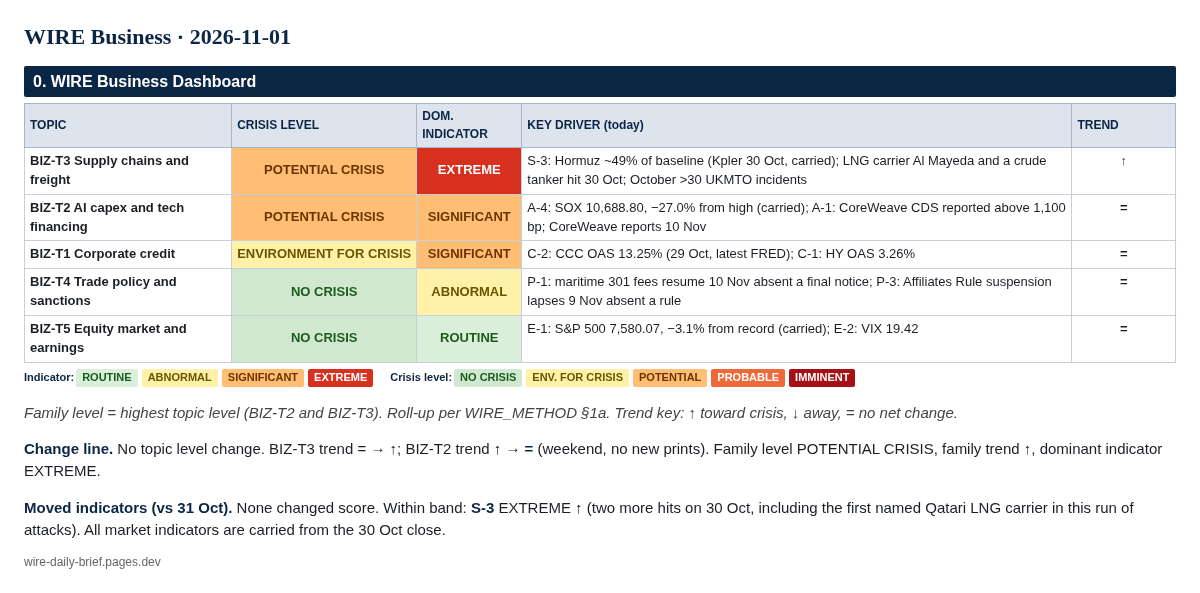
BLUF. WIRE Business holds at POTENTIAL CRISIS, trending toward crisis (↑), with the driver back in the Gulf over the weekend. Nakilat said its LNG carrier Al Mayeda was hit by "unidentified objects" in the Arabian Gulf on 30 Oct; the crew is safe and the ship operational. UKMTO separately reported a crude tanker struck by a projectile while leaving the Strait of Hormuz the same day, and counts more than 30 incidents in October, the most of any month of the war. Markets were closed, so no index, spread or flow reading moved: the chip index stays 27% below its high and FRED has not yet posted 30 Oct credit spreads, so BIZ-22 stays open. No prediction resolved today. A trade-calendar risk sits 9 Nov: the US export-control "Affiliates Rule" suspension lapses unless the Commerce Department extends it. The week ahead brings Apple (2 Nov), the midterms (3 Nov), container rates and a French national strike (5 Nov) and payrolls (6 Nov).
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | EXTREME | S-3: Hormuz ~49% of baseline (Kpler 30 Oct, carried); LNG carrier Al Mayeda and a crude tanker hit 30 Oct; October >30 UKMTO incidents | ↑ |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX 10,688.80, −27.0% from high (carried); A-1: CoreWeave CDS reported above 1,100 bp; CoreWeave reports 10 Nov | = |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.25% (29 Oct, latest FRED); C-1: HY OAS 3.26% | = |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1: maritime 301 fees resume 10 Nov absent a final notice; P-3: Affiliates Rule suspension lapses 9 Nov absent a rule | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P 500 7,580.07, −3.1% from record (carried); E-2: VIX 19.42 | = |
Family level = highest topic level (BIZ-T2 and BIZ-T3). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic level change. BIZ-T3 trend = → ↑; BIZ-T2 trend ↑ → = (weekend, no new prints). Family level POTENTIAL CRISIS, family trend ↑, dominant indicator EXTREME.
Moved indicators (vs 31 Oct). None changed score. Within band: S-3 EXTREME ↑ (two more hits on 30 Oct, including the first named Qatari LNG carrier in this run of attacks). All market indicators are carried from the 30 Oct close.
Attacks. Nakilat said its LNG carrier Al Mayeda was "hit by unidentified objects" while transiting the Arabian Gulf on the evening of 30 Oct; no crew were injured, there was no environmental impact, and the vessel is "in a safe condition, operational" while damage is assessed (Nakilat; Anadolu, 1 Nov). UKMTO warning 188-26 reported a projectile hitting a vessel's port side and causing a fire about 40 nm south of Lavan Island at 1800 UTC on 30 Oct, without naming the ship (EconoTimes). UKMTO also reported a crude tanker struck by an unidentified projectile on an outbound Hormuz transit (Anadolu, 31 Oct). UKMTO counts more than 30 incidents in the Strait, Gulf of Oman and Arabian Gulf in October, above March's 30 and 145 since 28 Feb (The National, 31 Oct). Flows. No Kpler briefing dated 31 Oct or 1 Nov was published (both URLs return 404), so S-3 carries 8,462 kbd, about 49% of the 17,147 kbd baseline for the 7 days to 28 Oct (Kpler, 30 Oct). The same briefing puts Fujairah and Oman bypass loadings about 36% above their pre-war baseline. Indicators. S-1 ABNORMAL ($4,429, carried to the 5 Nov print). S-2 ABNORMAL (carried). S-3 EXTREME (carried, ↑ within band). S-4 ABNORMAL. S-5 ABNORMAL (French national strike called for 5 Nov). Roll-up: 1 Extreme with no other indicator above Abnormal = POTENTIAL CRISIS (↑). Analyst Comment. A hit on a Qatari LNG carrier widens the target set from crude to gas, which matters for LNG freight and insurance even with the ship still sailing. We judge it likely (about 70%) that war-risk premiums for Gulf LNG calls rise this week, but we have no quote to confirm it (see Gaps). The next Kpler briefing remains the test for BIZ-16 (at or below 40%).
No new market prints. The SOX last closed at 10,688.80 on 30 Oct, 27.0% below its 14,634.72 high (Yahoo Finance history). CNBC notes Amazon was the third hyperscaler, after Alphabet and Meta, to report negative free cash flow, and says investors worry rising Big Tech debt signals wider stress as financial conditions tighten (CNBC week-ahead, 30 Oct). BondTerminal's 29 Oct brief has CoreWeave's 9.75% 2031 notes at 999 bp (yield to worst 14.81%, price 82.68) as of 27 Oct, before Friday's sell-off, and dates CoreWeave's Q3 results to 10 Nov (BondTerminal). AMD reports 3 Nov; Arm and Qualcomm 4 Nov (CNBC, above). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT (carried). A-3 ROUTINE (Nasdaq −7.8%, carried). A-4 SIGNIFICANT (carried). A-5 ABNORMAL. Roll-up: 3 Significant + 1 Abnormal = POTENTIAL CRISIS (=). Analyst Comment. Nothing new over the weekend changes the picture: BIZ-T2 is one Extreme short of PROBABLE CRISIS. The 10 Nov CoreWeave report is the likeliest A-1 catalyst this month.
FRED's latest values are still 29 Oct: HY OAS 3.26%, CCC OAS 13.25%, IG OAS 0.89% (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). Private-credit redemption pressure is easing but gates remain: Fitch-tracked data show nine of 15 non-traded BDCs still above their 5% caps (FinancialMarkets.com). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL (carried). C-6 ABNORMAL. Roll-up: 1 Significant + 2 Abnormal = ENVIRONMENT FOR CRISIS (=).
The Federal Register shows no USTR, BIS or OFAC rule from 30 Oct through the 2 Nov issue; the only item is a USTR staffing notice (FR API). The maritime Section 301 suspension still needs a final notice before fees resume on 10 Nov (FR 2026-21755). The one-year suspension of the BIS "Affiliates Rule" (export controls extended to firms 50%+ owned by listed entities) expires on 9 Nov under the current rule; the September truce extension to 10 Jan 2027 does not by itself extend it, so BIS must amend the date (BKL legal update). OFAC's latest action is an amended Iran general license (FF-1) on 29 Oct (OFAC, 29 Oct). MOFCOM confirms the "30-for-30" reciprocal tariff-cut lists are agreed but not yet in force (MOFCOM). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE (watch 9 Nov). P-4 ROUTINE. Roll-up: NO CRISIS (=). Analyst Comment. Two administrative deadlines, 9 and 10 Nov, now carry the US–China truce. A lapse of either would read as a P-2/P-3 move. We judge both extensions likely; see BIZ-13 and new BIZ-24.
Carried: S&P 500 7,580.07 on 30 Oct, 3.1% below its 7,818.93 record; VIX 19.42 (Yahoo Finance). FactSet still projects about 30% blended Q3 EPS growth, but the average beat is only 1.4% versus a 7.5% five-year average (CNBC, above). Apple reports after the close on 2 Nov. Indicators. E-1 to E-5 ROUTINE. Roll-up: NO CRISIS (=).
Resolved today: none. BIZ-22 (FRED HY OAS for 30 Oct above 3.26%) stays open because FRED has not yet posted the 30 Oct value.
Still open: BIZ-01, -02, -03, -04, -06, -07, -08, -09, -11, -12, -13, -14, -16, -19, -20, -22, -23.
New (dated 2026-11-01; logged in the prediction ledger): - BIZ-24: BIS publishes a rule or notice (Federal Register or bis.gov) dated 1–10 Nov 2026 that extends the Affiliates Rule suspension beyond 9 Nov 2026. 70%, likely. Resolve by 2026-11-11. - BIZ-25: The VIX closes at or above 20.00 on any trading day from 2 to 6 Nov 2026 (FRED VIXCLS, or Cboe/Yahoo if FRED lags). 60%, roughly even to likely. Resolve by 2026-11-09.
Nakilat; Anadolu Agency; EconoTimes (UKMTO 188-26); The National (UKMTO data); Kpler media briefing (30 Oct); CNBC; BondTerminal; Yahoo Finance; FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM); FinancialMarkets.com (Fitch data); Federal Register; BKL; OFAC; MOFCOM.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe