WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Tuesday, 3 November 2026 | Vol. 2026-307 | As of 030630 EST NOV 26
BLUF. WIRE Business stays at POTENTIAL CRISIS, and the trend turns back to ↑ as AI-financing stress spreads into credit and volatility. The chip index fell 3.4% to 10,328.33 on 2 Nov, 29.4% below its high, and Oracle priced $10 billion of bonds at 7–8.65% plus $10 billion of stock at an 11% discount. FRED's delayed 30 Oct prints show high-yield spreads widening 18 bp to 3.44%, which resolves BIZ-22 as a hit. The VIX closed at 21.15, so E-2 moves to ABNORMAL and BIZ-25 hits; the S&P 500 fell to 7,541.40, so BIZ-27 misses. In the Gulf, Brent settled $104.77 (−7.6%) on talks, then rose about 1–2% overnight after reported US strikes on Qeshm; a tug sank in the strait and Kpler puts Hormuz at 45% of normal. BIS still has six days to extend the Affiliates Rule suspension. Today: US midterms; AMD reports.
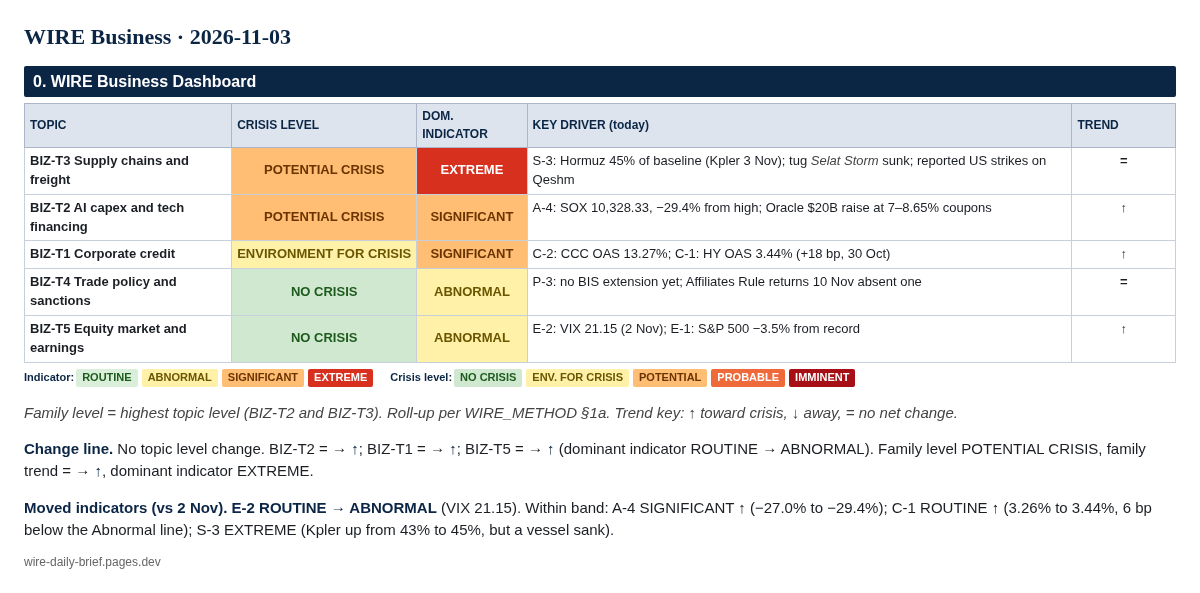
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | EXTREME | S-3: Hormuz 45% of baseline (Kpler 3 Nov); tug Selat Storm sunk; reported US strikes on Qeshm | = |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX 10,328.33, −29.4% from high; Oracle $20B raise at 7–8.65% coupons | ↑ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.27%; C-1: HY OAS 3.44% (+18 bp, 30 Oct) | ↑ |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-3: no BIS extension yet; Affiliates Rule returns 10 Nov absent one | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ABNORMAL | E-2: VIX 21.15 (2 Nov); E-1: S&P 500 −3.5% from record | ↑ |
Family level = highest topic level (BIZ-T2 and BIZ-T3). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. No topic level change. BIZ-T2 = → ↑; BIZ-T1 = → ↑; BIZ-T5 = → ↑ (dominant indicator ROUTINE → ABNORMAL). Family level POTENTIAL CRISIS, family trend = → ↑, dominant indicator EXTREME.
Moved indicators (vs 2 Nov). E-2 ROUTINE → ABNORMAL (VIX 21.15). Within band: A-4 SIGNIFICANT ↑ (−27.0% to −29.4%); C-1 ROUTINE ↑ (3.26% to 3.44%, 6 bp below the Abnormal line); S-3 EXTREME (Kpler up from 43% to 45%, but a vessel sank).
Attacks and strikes. NAVAREA IX warning 425/26 (15:00 UTC, 2 Nov) states the tug Selat Storm was "involved in a security incident and sunk" off Musandam (NAVAREA IX 425/26); the Maritime Executive links it to the 1 Nov projectile strike reported by UKMTO (Maritime Executive). US officials told AP and ABC that US forces made "limited defensive" strikes on Iran's Qeshm Island on 2 Nov after an Iranian missile downed a US drone (AP; ABC News). Talks continue (see the World Instability WIRE). Flows and prices. Kpler's 3 Nov briefing puts total Hormuz clearance at 7,789 kbd over the 7 days to 1 Nov, about 45% of the 17,147 kbd baseline; excluding Iranian-origin cargo, 6,461 kbd (38%). Fujairah and Oman loadings averaged 4,240 kbd, 24% above pre-war (Kpler, 3 Nov). Brent settled $104.77 on 2 Nov, down 7.6% (Business Times), then traded near $105.8–106.6 early on 3 Nov after the strike reports (CNBC). Indicators. S-1 ABNORMAL ($4,429, carried to the 5 Nov print). S-2 ABNORMAL (carried). S-3 EXTREME. S-4 ABNORMAL. S-5 ABNORMAL (French national strike 5 Nov). Roll-up: 1 Extreme = POTENTIAL CRISIS; trend = (flows edged up, but a sinking and US strikes offset it). Analyst Comment. Cheaper oil on 2 Nov priced diplomacy, not shipping: tanker crossings are still a fraction of normal and a vessel has now sunk. We hold BIZ-26 (60% of baseline by 13 Nov) unlikely, about 15%.
The SOX fell 3.37% to 10,328.33 on 2 Nov after a 7% drop on 30 Oct (Schwab Network; Yahoo Finance). The Nasdaq Composite fell 1.07% to 25,164.36, 8.8% below its 6 Oct record of 27,599.89 (FRED NASDAQCOM). Oracle filed and priced $10 billion of senior notes in five tranches (2029–2046) with coupons of 7% to 8.65%, and 86.2 million shares at $116, about 11% below the 30 Oct close; both close 4 Nov (CNBC; The Next Web). Its shares fell 8.8%. S&P rated the notes BBB- (S&P Global Ratings); Moody's affirmed Baa2 with a negative outlook, citing reliance on equity funding (Moody's via Fiscal.ai). Marvell agreed to buy Lumentum in an all-stock deal valued at $115 billion; Marvell fell about 13% (CNBC, above). Apple beat estimates (revenue $114.48 billion) but fell about 3% after hours on margin concerns (WSJ). Indicators. A-1 SIGNIFICANT (CoreWeave, carried). A-2 SIGNIFICANT (carried; Oracle's raise was completed, not pulled). A-3 ROUTINE (−8.8%). A-4 SIGNIFICANT (−29.4%). A-5 ABNORMAL. Roll-up: 3 Significant + 1 Abnormal = POTENTIAL CRISIS; trend ↑. Analyst Comment. The market is still funding the build-out, but at a price: an investment-grade borrower paying up to 8.65% and selling stock at a discount is a sign that the cost of AI capital is rising. We judge a SOX close below 10,000 by 13 Nov unlikely but close, about 40% (new BIZ-28). AMD reports tonight.
FRED has now posted 30 Oct: HY OAS 3.44% (from 3.26%), CCC OAS 13.27% (from 13.25%), IG OAS 0.94% (from 0.89%) (direct CSV download, 3 Nov 06:20 ET; BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM). Blackstone's BCRED prorated its third-quarter tender for a second quarter, accepting 5% of shares against requests near 10% (SQX Alts). Indicators. C-1 ROUTINE (↑ within band). C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL (carried). C-6 ABNORMAL (contractual 5% caps, no suspensions or wind-downs found). Roll-up: ENVIRONMENT FOR CRISIS; trend ↑ (broad widening on a risk-off day). Analyst Comment. The widening reached investment grade, not just the tail. We judge IG OAS at or above 1.00% by 13 Nov unlikely (about 35%; new BIZ-29).
Today's Federal Register public-inspection list has no BIS, OFAC or USTR document, only routine trade-remedy items (FR public inspection). The 2025 stay of the Affiliates Rule still ends 9 Nov, with reimposition on 10 Nov absent a new rule (Federal Register; Dechert). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE (deadline 9 Nov). P-4 ROUTINE. Roll-up: NO CRISIS (=). Analyst Comment. We still judge an extension likely (BIZ-24, 70%), but each quiet day lowers the odds of a clean handover.
The S&P 500 fell 0.51% to 7,541.40, 3.5% below its 7,818.93 record; the Dow rose 0.41% (CNBC; FRED SP500). The VIX closed at 21.15 (Yahoo Finance). At 05:06 ET today, S&P 500 futures were flat and Nasdaq-100 futures up 0.46% (Reuters via Investing.com). Indicators. E-1 ROUTINE. E-2 ABNORMAL. E-3 to E-5 ROUTINE. Roll-up: 1 Abnormal = NO CRISIS; trend ↑.
Resolved today: - BIZ-22 HIT. FRED BAMLH0A0HYM2 for 30 Oct is 3.44, above 3.26. Forecast 65%; Brier 0.1225. - BIZ-25 HIT. VIX closed 21.15 on 2 Nov (Yahoo Finance; FRED VIXCLS not yet posted). Forecast 60%; Brier 0.16. - BIZ-27 MISS. S&P 500 closed 7,541.40 on 2 Nov, below 7,580.07. Forecast 60%; Brier 0.36.
Still open: BIZ-01, -02, -03, -04, -06, -07, -08, -09, -11, -12, -13, -14, -16, -19, -20, -23, -24, -26.
New (dated 2026-11-03; logged in the prediction ledger): - BIZ-28: Any official SOX close below 10,000 from 3 to 13 Nov 2026. 40%, unlikely. Resolve by 2026-11-16. - BIZ-29: FRED BAMLC0A0CM (IG OAS) at or above 1.00 for any date from 2 to 13 Nov 2026. 35%, unlikely. Resolve by 2026-11-18.
NAVAREA IX 425/26; Maritime Executive; AP; ABC News; Kpler media briefing (3 Nov); Business Times; CNBC; Schwab Network; Yahoo Finance; FRED (NASDAQCOM, SP500, BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM); The Next Web; S&P Global Ratings; Moody's via Fiscal.ai; WSJ; SQX Alts; Federal Register; Dechert; Reuters via Investing.com.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe