WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Wednesday, 11 November 2026 | Vol. 2026-315 | As of 110640 EST NOV 26
BLUF. WIRE Business holds at POTENTIAL CRISIS but trends toward crisis, because the Hormuz supply-chain topic rose a level while AI-infrastructure financing eased. Kpler's 11 Nov briefing puts 7-day Total Hormuz Clearance at 5,114 kbd, about 30% of pre-war (preliminary floor), and ADNOC Logistics & Services confirmed one of its vessels was damaged in an attack inside UAE waters on 10 Nov. CoreWeave beat Q3 revenue ($3.661B) and raised guidance; its 5-year CDS was about 1,152 bp before the print, still in the distress band. The S&P 500 fell 0.38% to 7,520.93 after a hotter October CPI; FRED HY OAS tightened to 3.34% (9 Nov). Two calls resolve as hits: BIZ-16 (Kpler at or below 40%) and BIZ-36 (CoreWeave revenue beat).
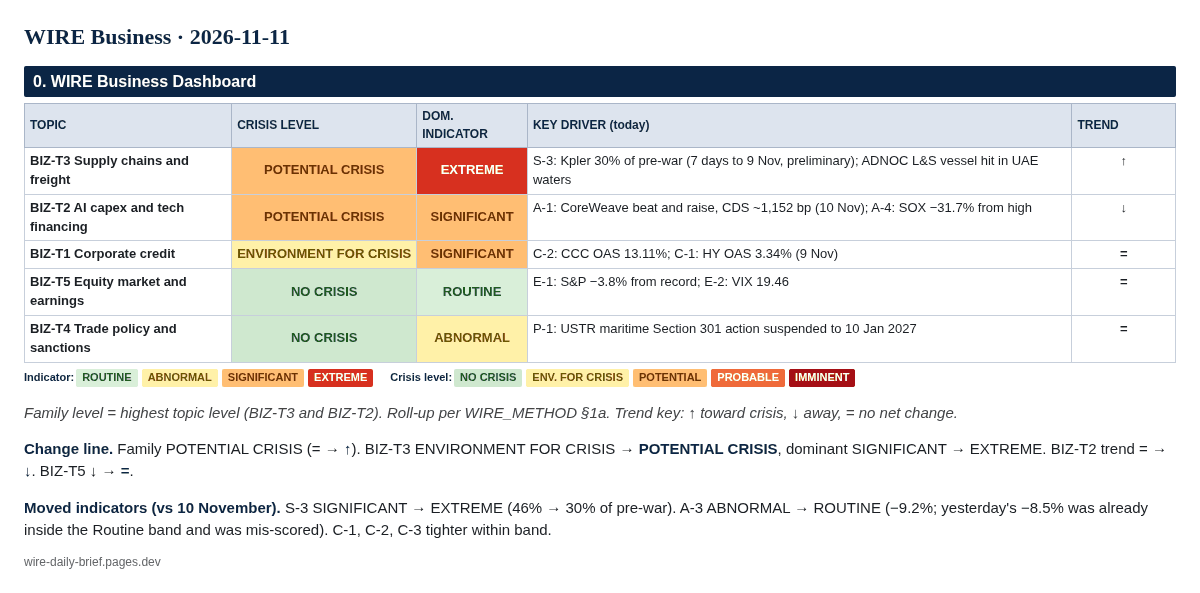
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | EXTREME | S-3: Kpler 30% of pre-war (7 days to 9 Nov, preliminary); ADNOC L&S vessel hit in UAE waters | ↑ |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-1: CoreWeave beat and raise, CDS ~1,152 bp (10 Nov); A-4: SOX −31.7% from high | ↓ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.11%; C-1: HY OAS 3.34% (9 Nov) | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P −3.8% from record; E-2: VIX 19.46 | = |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | P-1: USTR maritime Section 301 action suspended to 10 Jan 2027 | = |
Family level = highest topic level (BIZ-T3 and BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. Family POTENTIAL CRISIS (= → ↑). BIZ-T3 ENVIRONMENT FOR CRISIS → POTENTIAL CRISIS, dominant SIGNIFICANT → EXTREME. BIZ-T2 trend = → ↓. BIZ-T5 ↓ → =.
Moved indicators (vs 10 November). S-3 SIGNIFICANT → EXTREME (46% → 30% of pre-war). A-3 ABNORMAL → ROUTINE (−9.2%; yesterday's −8.5% was already inside the Routine band and was mis-scored). C-1, C-2, C-3 tighter within band.
Kpler's 11 Nov briefing, read directly, reports Total Hormuz Clearance of 5,114 kbd over the 7 days to 9 Nov, about 30% of the 17,148 kbd pre-war level; adding Fujairah/Oman loadings gives 43% and the regional total with Red Sea volumes 57%. Kpler says the latest days are preliminary and "have typically settled 1.5 to 2 times higher" (Kpler 11 Nov). ADNOC L&S confirmed a vessel "sustained damage following an attack in the UAE's territorial waters" on the afternoon of 10 Nov (ADNOC L&S). UKMTO reported a tanker struck about 19 nmi northeast of Lima, Oman, and JMIC holds the Hormuz threat level at severe (World Oil). Reuters counts 10 attacks in and around the strait so far in November (37 in October), and Iran's Revolutionary Guards navy said two tankers caught fire after hitting naval mines on an "unauthorized route" (Reuters via Yahoo Finance; AGBI). Brent was $92.77 (+$1.28) at 09:34 GMT (04:34 EST) after Tuesday's two-month low (Reuters, same link). Drewry WCI $4,389 (5 Nov) carried; next print 12 Nov. Indicators. S-1 ABNORMAL (carried). S-2 ABNORMAL (carried). S-3 EXTREME. S-4 ABNORMAL (carried). S-5 ABNORMAL (carried). Roll-up: 1 Extreme, no other above Abnormal = POTENTIAL CRISIS; trend ↑. Analyst Comment. Even if the preliminary floor settles 1.5 times higher, clearance would sit near 45%, still more than half below normal; a confirmed attack inside UAE waters and a party claim of mine strikes add to the flow signal. We judge a Kpler read at or above 60% by 20 Nov (BIZ-41, logged at 55%) now unlikely (about 30%).
CoreWeave reported Q3 revenue of $3,661M (from $1,365M), net loss $709M, interest expense $846M, backlog about $132.5B; it raised 2026 revenue guidance to $13.0–13.3B and capex to $37–39B, and guided Q4 interest expense to $1.05–1.15B (CoreWeave IR). LSEG consensus was $3.55B (CNBC). Its 5-year CDS stood around 1,152 bp on Tuesday after closing at 1,278 bp on 5 Nov, and its 2031 bond yielded 15.5% (CNBC). On the call it said it will not use the unsecured bond market at current yields and expects about $9B in customer prepayments over three months (Dow Jones via Morningstar); shares were up about 11% premarket (CNBC). Anthropic launched its roadshow at $70–78 a share for 825M shares (Anthropic); pricing is expected 18 Nov (CNBC). SOX closed 9,998.33 on 10 Nov (−31.7% from 14,634.72) (FRED NASDAQSOX); the Nasdaq Composite closed 25,065.87 (−9.2% from 27,599.89) (AP). Indicators. A-1 SIGNIFICANT. A-2 SIGNIFICANT (carried). A-3 ROUTINE. A-4 SIGNIFICANT. A-5 ABNORMAL (carried). Roll-up: 3 Significant = POTENTIAL CRISIS; trend ↓. Analyst Comment. Prepayments and secured delayed-draw loans shift funding risk to customers rather than remove it; A-1 leaves the distress band only if CDS clears 1,000 bp (BIZ-19 open).
FRED shows 9 Nov: HY OAS 3.34%, CCC OAS 13.11%, IG OAS 0.91% (BAMLH0A0HYM2; BAMLH0A3HYC; BAMLC0A0CM). The US cash bond market is closed today on SIFMA's holiday recommendation (SIFMA). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 to C-6 carried. Roll-up: ENVIRONMENT FOR CRISIS; trend =.
USTR further suspended the maritime, logistics and shipbuilding Section 301 action, including port fees and crane duties, through 11:59 p.m. ET on 9 Jan 2027 (Federal Register 2026-22867). The BIS affiliates-rule stay runs to 10 Jan 2027 (carried). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: NO CRISIS; trend =.
The S&P 500 closed 7,520.93 (−0.38%), 3.8% below its 7,818.93 record, after October CPI rose 0.4% (core 0.3%), both above forecast (FRED SP500; CNBC). VIX closed 19.46 (Yahoo Finance/Cboe). At 05:04 ET S&P futures were +0.74% and Nasdaq-100 futures +1.67% (Reuters via Devdiscourse). Indicators. E-1 ROUTINE. E-2 ROUTINE. E-3 to E-5 ROUTINE (carried). Roll-up: NO CRISIS; trend =.
Resolved today: - BIZ-16 HIT (p 0.30, Brier 0.49): Kpler 11 Nov briefing, 5,114 kbd (~30%), below the 6,859 kbd line. - BIZ-36 HIT (p 0.60, Brier 0.16): CoreWeave Q3 revenue $3,661M vs $3.54B line.
Due soon: BIZ-02 (12 Nov, Drewry), BIZ-03 (13 Nov), BIZ-32 (16 Nov), BIZ-29 (18 Nov).
New (dated 2026-11-11; logged in the prediction ledger): - BIZ-42: Anthropic Class A shares close their first Nasdaq trading day above the IPO price, if trading begins by 30 Nov. 65%, likely. Resolve by 2026-12-02. - BIZ-43: A Kpler briefing dated 12–20 Nov reports 7-day Total Hormuz Clearance at or below 35% of pre-war. 45%, roughly even chance. Resolve by 2026-11-23.
Kpler media briefing 11 Nov; ADNOC L&S; World Oil; Reuters via Yahoo Finance and Devdiscourse; AGBI; CoreWeave IR; CNBC; Dow Jones via Morningstar; Anthropic; AP; FRED (NASDAQSOX, SP500, BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM); Yahoo Finance (Cboe VIX); SIFMA; Federal Register 2026-22867.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or voting advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe