WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Saturday, 14 November 2026 | Vol. 2026-318 | As of 140700 EST NOV 26
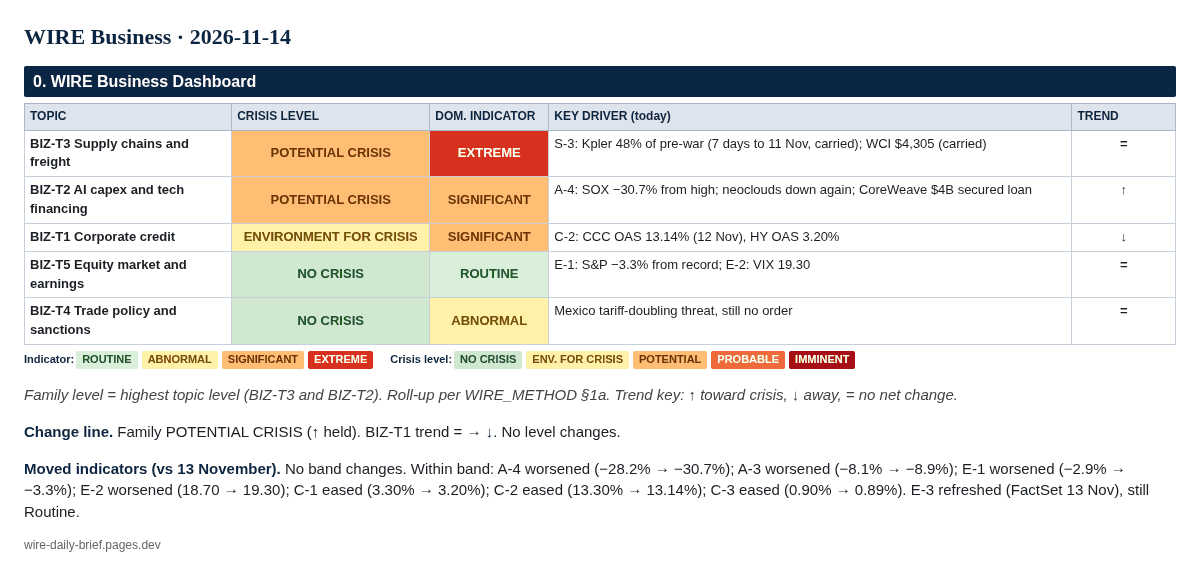
BLUF. WIRE Business holds at POTENTIAL CRISIS, trend toward crisis, as the Nvidia leadership shock spread through AI-linked stocks for a second day. On Friday 13 Nov the PHLX Semiconductor Index fell to 10,146.32, 30.7% below its high, Nvidia fell 2.0% to $162.85 and closed below $4 trillion in market value, and CoreWeave fell 6.1% to $53.13 (intraday low $49.24). CoreWeave is marketing a $4 billion loan secured by Meta contracts. Broad credit moved the other way: FRED HY OAS tightened to 3.20% and CCC OAS to 13.14% (12 Nov). The S&P 500 closed 7,561.67, 3.3% below its record, and VIX 19.30. Hormuz flows are still Extreme (Kpler 48%, carried). BIZ-03 and BIZ-32 resolve as misses. Markets reopen Monday; Nvidia reports 17 Nov and Anthropic is due to list 19 Nov.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | EXTREME | S-3: Kpler 48% of pre-war (7 days to 11 Nov, carried); WCI $4,305 (carried) | = |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4: SOX −30.7% from high; neoclouds down again; CoreWeave $4B secured loan | ↑ |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.14% (12 Nov), HY OAS 3.20% | ↓ |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P −3.3% from record; E-2: VIX 19.30 | = |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | Mexico tariff-doubling threat, still no order | = |
Family level = highest topic level (BIZ-T3 and BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. Family POTENTIAL CRISIS (↑ held). BIZ-T1 trend = → ↓. No level changes.
Moved indicators (vs 13 November). No band changes. Within band: A-4 worsened (−28.2% → −30.7%); A-3 worsened (−8.1% → −8.9%); E-1 worsened (−2.9% → −3.3%); E-2 worsened (18.70 → 19.30); C-1 eased (3.30% → 3.20%); C-2 eased (13.30% → 13.14%); C-3 eased (0.90% → 0.89%). E-3 refreshed (FactSet 13 Nov), still Routine.
No new Kpler briefing or Drewry print since Friday's edition. Kpler's 13 Nov briefing put 7-day Total Hormuz Clearance at 8,264 kbd, about 48% of pre-war (Kpler 13 Nov); Drewry's WCI stood at $4,305/40ft on 12 Nov (Drewry). Kpler daily data cited by GMT Eight show three commodity ships transiting Hormuz on the latest day counted, against a 10-day average of about 15, and 22 through Bab el-Mandeb against 26 (GMT Eight). Brent settled at $95.84 on Friday (Straits Daily Brief). Indicators. S-1 ABNORMAL (carried). S-2 ABNORMAL (carried). S-3 EXTREME (carried). S-4 ABNORMAL (carried). S-5 ABNORMAL (carried). Roll-up: 1 Extreme, none other above Abnormal = POTENTIAL CRISIS; trend =. Analyst Comment. The daily transit counts are noisy and do not replace Kpler's weekly clearance series, but a low daily count makes a fall back toward BIZ-43's 35% line more plausible than last week's two 40%-plus prints suggested.
SOX closed 10,146.32 on 13 Nov (−3.4% on the day; −30.7% from 14,634.72) and the Nasdaq Composite 25,136.27 (−0.91%; −8.9% from 27,599.89) (FRED NASDAQSOX; CNBC). Nvidia fell 2.01% to $162.85, closing below $4 trillion in market value for the first time since July 2025 and down 12.75% on the week, its sixth straight weekly decline (CNBC). Reuters reported CoreWeave and Nebius down about 9% intraday, AMD down more than 10% intraday, and Nvidia-backed Nscale amending its IPO filing to show a $1.7 billion nine-month net loss (Investing.com / Reuters). CoreWeave closed $53.13 (−6.13%) after an intraday low of $49.24 (Yahoo Finance). Semafor reports CoreWeave is seeking a $4 billion loan backed by Meta contracts and arranged by Morgan Stanley and MUFG, targeting about 7.5% all-in against nearly 16% yields on its unsecured bonds (Semafor). Anthropic's IPO books are reported about 6x covered at a $70–78 range (StockAnalysis; CNBC). Indicators. A-1 SIGNIFICANT (CoreWeave CDS last verified ~1,155 bp; unsecured yields near 16%). A-2 SIGNIFICANT (carried). A-3 ROUTINE. A-4 SIGNIFICANT. A-5 ABNORMAL (carried). Roll-up: 3 Significant = POTENTIAL CRISIS; trend ↑ (second day of sector-wide losses; SOX now past 30%). Analyst Comment. The market is splitting AI finance in two: contract-backed, investment-grade-style debt still clears, while equity and unsecured debt of the most leveraged builders reprice. A failed or repriced CoreWeave syndication, expected to start as early as the week of 16 Nov, would be the clearest A-2 signal.
FRED values for 12 Nov: HY OAS 3.20%, CCC OAS 13.14%, IG OAS 0.89%; next release 16 Nov (BAMLH0A0HYM2; BAMLH0A3HYC; BAMLC0A0CM). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL (carried). C-6 ABNORMAL (carried). Roll-up: ENVIRONMENT FOR CRISIS; trend ↓ (all three spread series tightened). Analyst Comment. Broad credit is not confirming the AI-equity stress; the 13 Nov print, due Monday, will show whether Friday's tech selloff reached spreads.
The 13 Nov Federal Register issue contains no action on Mexico tariffs; the 12 Nov threat to double them came with no deadline or legal basis named (Federal Register 13 Nov; Reuters). OFAC's 13 Nov actions were counter-narcotics and counter-terrorism designations of Guatemalan trafficking groups (OFAC). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: NO CRISIS; trend =.
The S&P 500 closed 7,561.67 (−0.40%), 3.3% below its 7,818.93 record, but gained 2.5% on the week; the Dow rose 0.1% to 52,347.55 (AP; CNBC). VIX closed 19.30 (WSJ). FactSet's 13 Nov Earnings Insight puts Q3 blended EPS growth at 31.9% (FactSet). Indicators. E-1 ROUTINE. E-2 ROUTINE. E-3 ROUTINE. E-4 ROUTINE (carried). E-5 ROUTINE (carried). Roll-up: NO CRISIS; trend =.
Resolved today: - BIZ-03 (S&P 500 record close above 7,818.93 by 13 Nov, 45%): MISS, 13 Nov close 7,561.67. Brier 0.2025. - BIZ-32 (VIX close ≥30 on any day 6–13 Nov, 40%): MISS, highest close 25.64 on 6 Nov. Brier 0.16.
Due soon: BIZ-29 (IG OAS ≥1.00 from 2–13 Nov; readings through 12 Nov peak at 0.93; scored when the 13 Nov FRED value posts 16 Nov), BIZ-07 (19 Nov), BIZ-01/04/46 (20 Nov), BIZ-47 (CoreWeave close <$50 by 20 Nov; intraday low $49.24 does not count).
New (dated 2026-11-14; logged in the prediction ledger): - BIZ-49: Anthropic prices its IPO above $78.00, the top of its range, by 20 Nov. 55%, roughly even chance. Resolve by 2026-11-23. - BIZ-50: SOX closes below 10,000.00 on any trading day 16–20 Nov. 55%, roughly even chance. Resolve by 2026-11-23. - BIZ-51: The US formally raises tariffs on Mexican imports (proclamation, order or Federal Register notice) by 31 Dec. 25%, unlikely. Resolve by 2027-01-04.
FRED (NASDAQSOX, BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM, VIXCLS); CNBC; AP; WSJ market data; Yahoo Finance; Reuters via Investing.com; Semafor; StockAnalysis; FactSet Earnings Insight; Kpler media briefing 13 Nov; Drewry WCI; GMT Eight; Straits Daily Brief; Federal Register; OFAC.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or voting advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe