WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Economics editions
UNCLASSIFIED // OPEN SOURCE | Thursday, 22 October 2026 | Vol. 2026-295 | First full edition | As of 220700 EDT OCT 26
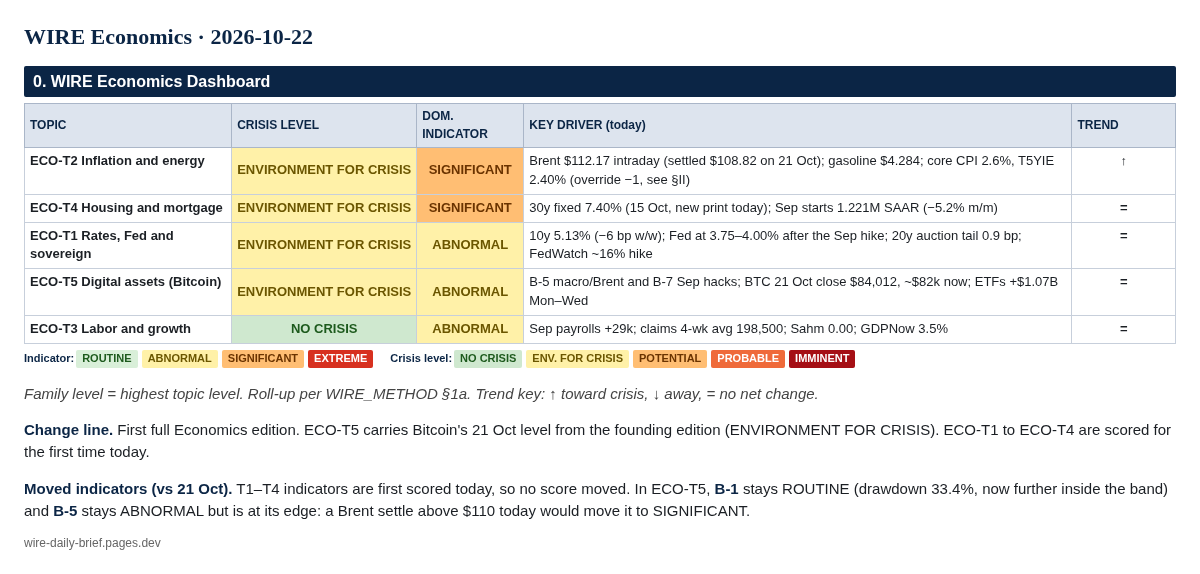
BLUF. WIRE Economics opens at ENVIRONMENT FOR CRISIS (↑), and the pressure is energy, not core inflation. Brent rose to $112.17 at 0818 GMT today, its highest since 18 May, after new Houthi strikes in Saudi Arabia (Reuters); US regular gasoline averaged $4.284 (EIA, 19 Oct); and the 30-year fixed mortgage is 7.40% (Freddie Mac, 15 Oct). Underlying inflation is still contained: core CPI is 2.6% y/y and the 5-year breakeven 2.40%. The 10-year Treasury yield is 5.13%, down 6 bp on the week, and Wednesday's 20-year auction cleared with a small 0.9 bp tail. Labor is soft but not breaking (September payrolls +29k, Sahm indicator 0.00). Bitcoin holds at ENVIRONMENT FOR CRISIS (=): it closed Wednesday at $84,012 and fell back near $82k this morning, while US spot ETFs took in +$524.8M on Wednesday. CME FedWatch prices about a 16% chance of a hike on 28 Oct (BTC-05).
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| ECO-T2 Inflation and energy | ENVIRONMENT FOR CRISIS | SIGNIFICANT | Brent $112.17 intraday (settled $108.82 on 21 Oct); gasoline $4.284; core CPI 2.6%, T5YIE 2.40% (override −1, see §II) | ↑ |
| ECO-T4 Housing and mortgage | ENVIRONMENT FOR CRISIS | SIGNIFICANT | 30y fixed 7.40% (15 Oct, new print today); Sep starts 1.221M SAAR (−5.2% m/m) | = |
| ECO-T1 Rates, Fed and sovereign | ENVIRONMENT FOR CRISIS | ABNORMAL | 10y 5.13% (−6 bp w/w); Fed at 3.75–4.00% after the Sep hike; 20y auction tail 0.9 bp; FedWatch ~16% hike | = |
| ECO-T5 Digital assets (Bitcoin) | ENVIRONMENT FOR CRISIS | ABNORMAL | B-5 macro/Brent and B-7 Sep hacks; BTC 21 Oct close $84,012, ~$82k now; ETFs +$1.07B Mon–Wed | = |
| ECO-T3 Labor and growth | NO CRISIS | ABNORMAL | Sep payrolls +29k; claims 4-wk avg 198,500; Sahm 0.00; GDPNow 3.5% | = |
Family level = highest topic level. Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. First full Economics edition. ECO-T5 carries Bitcoin's 21 Oct level from the founding edition (ENVIRONMENT FOR CRISIS). ECO-T1 to ECO-T4 are scored for the first time today.
Moved indicators (vs 21 Oct). T1–T4 indicators are first scored today, so no score moved. In ECO-T5, B-1 stays ROUTINE (drawdown 33.4%, now further inside the band) and B-5 stays ABNORMAL but is at its edge: a Brent settle above $110 today would move it to SIGNIFICANT.
Statement of Normalcy. Routine is a 10-year yield under 4.5%, weekly moves under 20 bp, Fed actions in line with futures pricing, and auctions that clear without large tails. Yields. The 10-year par yield was 5.13% on 21 Oct, against 5.19% on 14 Oct (−6 bp on the week) and 5.31% on 5 Oct. The 2-year was 4.81% and the 30-year 5.42% (Treasury daily par yield curve; FRED DGS10). Auction. The $13B 20-year reopening on 21 Oct stopped at 5.469%, against 5.459% when-issued at the bid deadline, a tail of about 1 bp. Bid-to-cover was 2.73 (2.57 in September) (CME/Econoday; FinancialJuice). Fed. The target range is 3.75–4.00% after the September hike. CME FedWatch on 21 Oct priced 83.9% hold / 16.1% hike for 28 Oct, and about 76% odds of a cumulative 25 bp hike by December (Longbridge/Zhitong citing CME FedWatch). The Fed is in its pre-meeting blackout. Indicators. 10y level ABNORMAL (5.13%; band 4.5–5.25%). Weekly move ROUTINE (−6 bp). Fed vs pricing ABNORMAL (the September hike stands; next test 28 Oct). Auctions ROUTINE. Term premium and foreign sovereign spreads not collected today (see GAPS). Roll-up: 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Analyst Comment. The long end has eased since early October as money moved into Treasuries during the AI-credit scare (see WIRE Business), which takes some pressure off. A 10-year yield back above 5.25% would score Significant. The FOMC on 28 Oct is the decisive event: a second straight hike would move the Fed indicator to Significant and lift ECO-T1 and B-5 together.
Statement of Normalcy. Routine is core CPI under 3% y/y, a 5-year breakeven under 2.6%, Brent under $85 and gasoline under $3.50. Prices. September CPI rose 0.6% m/m and 3.7% y/y. Gasoline accounted for more than half of the monthly rise and is up 34.2% y/y. Core CPI rose 0.3% m/m and 2.6% y/y (BLS CPI, 14 Oct). September PPI final demand was +1.3% m/m and +6.3% y/y (BLS, 15 Oct, as carried in the founding editions). The 5-year breakeven was 2.40% on 21 Oct (FRED T5YIE). Energy. December Brent settled at $108.82 on 21 Oct. It then rose to $112.17 by 0818 GMT today (high $112.55), the highest since 18 May, after Houthi strikes on Saudi targets. The US ordered some diplomats out of Saudi Arabia (Reuters via Yahoo Finance, 22 Oct). US regular gasoline averaged $4.284/gal on 19 Oct, down from $4.478 on 21 Sep (EIA via FRED GASREGW). Indicators. Core CPI ROUTINE. T5YIE ROUTINE. Brent SIGNIFICANT ($100–120). Gasoline SIGNIFICANT ($4.25–5.00, near the lower edge). PPI not banded; noted. The formula gives 2 Significant = POTENTIAL CRISIS. Override −1 to ENVIRONMENT FOR CRISIS: both Significant reads come from the same oil shock, while core inflation and market inflation expectations stay Routine. Trend ↑ on today's Brent move. Analyst Comment. The topic's question is whether inflation is re-accelerating enough to force tightening into an oil shock. So far the shock is passing through to headline prices, not to core prices or expectations. The override would be withdrawn if the breakeven rises above 2.6% or core CPI reaches 3%. The October CPI is due 10 Nov.
Statement of Normalcy. Routine is payroll gains above +75k, claims (4-week average) under 250k, a Sahm reading under 0.3 and GDPNow above 1%. Data. September payrolls rose +29k to 159.044M. The unemployment rate rose to 4.2% (BLS Employment Situation; FRED PAYEMS). The 4-week average of initial claims was 198,500 (week to 10 Oct; new print today) (FRED IC4WSA). The real-time Sahm indicator was 0.00 for September (FRED SAHMREALTIME). Atlanta Fed GDPNow is 3.5% for Q3 (20 Oct) (Atlanta Fed). ISM manufacturing PMI was 54.5 in September, with prices paid at 77.9 (ISM via PR Newswire). Indicators. Payrolls ABNORMAL (0 to +75k). Claims ROUTINE. Sahm ROUTINE. GDPNow ROUTINE. ISM ROUTINE. Roll-up: 1 Abnormal = NO CRISIS (=). Analyst Comment. Hiring is slow but layoffs are not rising, and output is growing. The ISM prices index at 77.9 links this topic back to ECO-T2. The October jobs report (6 Nov) and the Q3 GDP advance estimate (29 Oct) are the next tests.
Statement of Normalcy. Routine is a 30-year fixed rate under 6.5%, with starts and pending sales moving within their normal monthly ranges. Data. Freddie Mac's 30-year fixed was 7.40% on 15 Oct, the same as on 8 Oct and up from 6.95% on 17 Sep (FRED MORTGAGE30US). The next print is due today. September housing starts were 1.221M SAAR, −5.2% m/m and −7.4% y/y. Permits were 1.400M, and single-family permits fell 4.0% (Census, 20 Oct). Indicators. 30y fixed SIGNIFICANT (7.25–8%). Starts noted (no band set; decline within the ±11.8% confidence interval). NAR pending sales and MBA delinquency not collected today. Roll-up: 1 Significant = ENVIRONMENT FOR CRISIS (=). Analyst Comment. The 10-year yield fell about 18 bp from 5 to 21 Oct, so today's Freddie Mac print may ease. Brent's jump is the risk to that. A housing-credit event is not in view. The pressure shows in volumes and affordability, not in defaults.
Price. The 21 Oct UTC close was $84,011.97 (high $84,840) on Yahoo. CoinGecko's 00:00 UTC 22 Oct value was $84,082.27 (Yahoo; CoinGecko). BTC then gave back the move. It traded under $82,000 this morning, and CoinGlass counted about $431M of liquidations in 24 hours (CoinDesk, 22 Oct). Drawdown from the ~$126.2k all-time high is 33.4% at the close. The 30-day realized volatility, computed from Yahoo daily closes, is about 23% annualized. Flows and plumbing. US spot ETFs took in +$524.8M on 21 Oct (IBIT +$235.0M, FBTC +$212.7M). Monday to Wednesday totals +$1,074.7M (Farside). USDT was at $0.9992 and USDC at $0.9997 (CoinGecko API). Hashrate is about 1,038 EH/s against a 30-day mean of about 999 EH/s. The last retarget was +5.92%, and the next is estimated at +4.84% (mempool.space). Fear & Greed is 68 (Alternative.me). PeckShield counted $766M in September hack losses, led by Bitget (~$387M) (Crypto Economy). The CLARITY Act remains stalled after cloture failed 49–50 on 15 Sep (Orrick). Indicators. B-1 ROUTINE. B-2 ROUTINE (+1.3% day, +3.0% week). B-3 ROUTINE (~23%; above the 20% compression line). B-4 ROUTINE (inflows). B-5 ABNORMAL (Brent settle $108.82; FedWatch ~16% hike). B-7 ABNORMAL (Bitget, 24 Sep; drops out of the 30-day window after 24 Oct if no new hack over $100M). B-6, B-8, B-9 and B-10 ROUTINE. Roll-up: 2 Abnormal = ENVIRONMENT FOR CRISIS (=). Tripwires (B-7/B-8 Extreme) not met. Analyst Comment. Strong ETF demand did not hold the price above $84k once tech futures and oil turned. The macro channel (B-5) is the one to watch. A Brent settle above $110, or a hike on 28 Oct, would make B-5 Significant. Low realized volatility near 23% means the range is compressed, so a break in either direction is plausible.
Open legacy calls (no resolution today): BTC-05 (hike on 28 Oct, 35%): FedWatch ~16%, trending miss. BTC-06 (<$78k close by 28 Oct): low close since 16 Oct is $81,382; not hit. BTC-07 (>$85k close by 28 Oct): 21 Oct close $84,012; not hit, intraday high $84,840. BTC-08 (net-inflow week 19–23 Oct): +$1,074.7M through Wednesday; trending hit, resolves 24 Oct. BTC-01 to BTC-04 run to 31 Dec. New (dated 2026-10-22; logged in the prediction ledger): - ECO-01: Freddie Mac's 30-year fixed (FRED MORTGAGE30US) prints at or below 7.25% in any weekly release from 22 Oct to 19 Nov 2026. 35%, unlikely. Resolve by 2026-11-19. - ECO-02: The 10-year Treasury yield (FRED DGS10 / Treasury par curve) closes at or above 5.25% on any date from 23 Oct to 20 Nov 2026. 40%, roughly even to unlikely. Resolve by 2026-11-20.
U.S. Treasury daily par yield curve; FRED (DGS10, T5YIE, IC4WSA, SAHMREALTIME, PAYEMS, MORTGAGE30US, GASREGW); BLS (CPI, Employment Situation); Census New Residential Construction (20 Oct); Atlanta Fed GDPNow; ISM via PR Newswire; CME/Econoday and FinancialJuice (20-year auction); Longbridge/Zhitong (CME FedWatch); Reuters via Yahoo Finance (22 Oct); Farside Investors; Yahoo Finance; CoinGecko; CoinDesk (22 Oct); mempool.space; Alternative.me; Crypto Economy (PeckShield); Orrick.
WIRE Economics | WIRE Desk | Open-source analysis. Not investment, legal or tax advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe