WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe
Download PDF · Dashboard image · All Business editions
UNCLASSIFIED // OPEN SOURCE | Monday, 16 November 2026 | Vol. 2026-320 | As of 160700 EST NOV 26
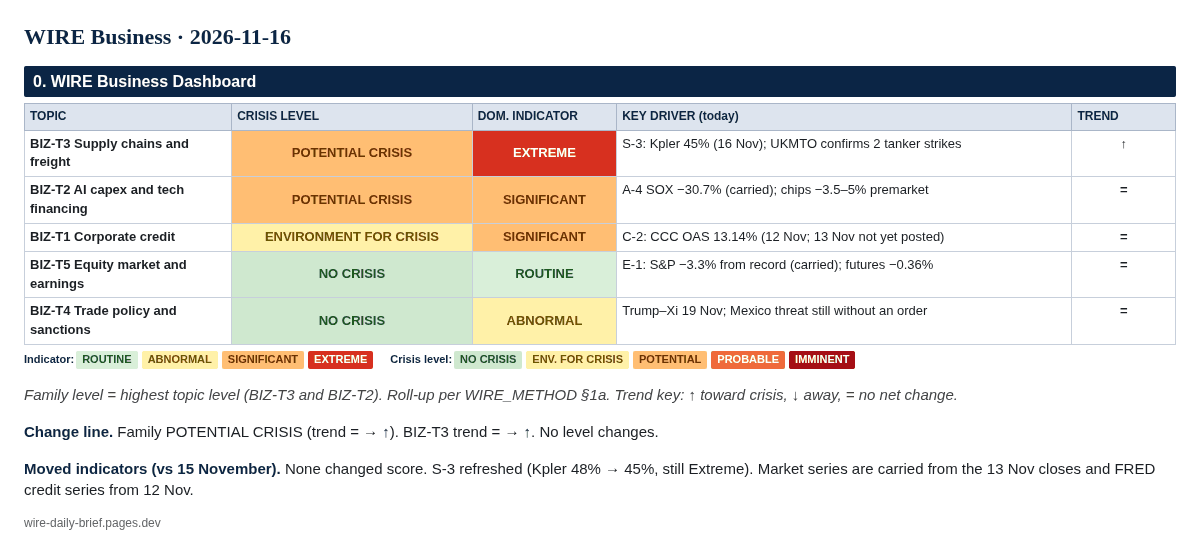
BLUF. WIRE Business holds at POTENTIAL CRISIS, and the trend turns toward crisis because attacks on Hormuz shipping are now confirmed. UKMTO confirmed a tanker attacked on 15 Nov as it approached the strait, and a second tanker hit by a projectile at 05:58 UTC on 16 Nov while leaving it. Kpler's 16 Nov briefing puts the 7-day Total Hormuz Clearance at 45% of pre-war, down from 48%. Iran's claims of mine strikes on 14–16 Nov remain unverified. At 05:08 ET, Nasdaq 100 futures were −0.97% and chipmakers were down 3.5–5% before the open. The FT reports that the former Nvidia chief executive is weighing a return. Equity and VIX readings carry Friday's closes. FRED has not yet posted credit data for 13 Nov, so BIZ-29 stays open. No calls resolved today; BIZ-55 to BIZ-57 are new. Nvidia reports 17 Nov, Anthropic prices 18 Nov, and Trump meets Xi 19 Nov.
| TOPIC | CRISIS LEVEL | DOM. INDICATOR | KEY DRIVER (today) | TREND |
|---|---|---|---|---|
| BIZ-T3 Supply chains and freight | POTENTIAL CRISIS | EXTREME | S-3: Kpler 45% (16 Nov); UKMTO confirms 2 tanker strikes | ↑ |
| BIZ-T2 AI capex and tech financing | POTENTIAL CRISIS | SIGNIFICANT | A-4 SOX −30.7% (carried); chips −3.5–5% premarket | = |
| BIZ-T1 Corporate credit | ENVIRONMENT FOR CRISIS | SIGNIFICANT | C-2: CCC OAS 13.14% (12 Nov; 13 Nov not yet posted) | = |
| BIZ-T5 Equity market and earnings | NO CRISIS | ROUTINE | E-1: S&P −3.3% from record (carried); futures −0.36% | = |
| BIZ-T4 Trade policy and sanctions | NO CRISIS | ABNORMAL | Trump–Xi 19 Nov; Mexico threat still without an order | = |
Family level = highest topic level (BIZ-T3 and BIZ-T2). Roll-up per WIRE_METHOD §1a. Trend key: ↑ toward crisis, ↓ away, = no net change.
Change line. Family POTENTIAL CRISIS (trend = → ↑). BIZ-T3 trend = → ↑. No level changes.
Moved indicators (vs 15 November). None changed score. S-3 refreshed (Kpler 48% → 45%, still Extreme). Market series are carried from the 13 Nov closes and FRED credit series from 12 Nov.
UKMTO cited Indian shipping authorities in confirming that a tanker was attacked in the Arabian Gulf on 15 Nov as it approached Hormuz; the crew were safe. On 16 Nov it issued an alert that an outbound tanker was struck by an unknown projectile at 05:58 UTC, causing an engine-room fire with no casualties. The security firm Vanguard Tech named the vessels as the VLCC Al Dhannah and the Panama-flagged On Phoenix, about 3 nm off Oman (Seatrade Maritime; Anadolu). Iran's forces now claim six tankers caught fire on 15–16 Nov, including a VLCC they say sank. Reuters could not verify this, and the IRGC video shows no identifiable ship (Arab News/Reuters; CNBC). Kpler's 16 Nov briefing has Total Hormuz Clearance averaging 7,708 kbd over the 7 days to 14 Nov (45% of 17,148 kbd). Mideast Gulf VLCC loadings fell to 7.4 mbd in early November from 9.3 mbd in October (Kpler). AIS showed 6 crossings on 15 Nov (hormuz.now). Brent was $95.15 early Monday (−0.7%), after the IEA forecast a Q4 surplus (CNBC). Indicators. S-1 ABNORMAL (WCI $4,305, 12 Nov, carried). S-2 ABNORMAL (Oct: Suez ~66%, Bab el-Mandeb ~54%, carried). S-3 EXTREME (45%). S-4 ABNORMAL (carried). S-5 ABNORMAL (carried). Roll-up: 1 Extreme = POTENTIAL CRISIS; trend ↑ (attacks confirmed, clearance lower). Analyst Comment. Two strikes are now confirmed in the corridor Iran calls unauthorized, so the desk no longer reads the Iranian claims as pure messaging. Kpler warns that its latest days usually revise up 1.5–2x, so 45% may prove a floor. Oil is falling despite the attacks, which suggests the market sees Hormuz as a freight and insurance problem more than a supply problem.
At 05:08 ET, Intel, AMD, Broadcom and Micron were down 3.5–5% before the open, CoreWeave −5.4%, Nebius −5.5%, and Dell and HP −5.1% each. Nvidia was −2.2% after its longest weekly losing streak since October 2012 (Reuters via Investing.com). The FT reports that the former chief executive is discussing a return with allies (RTÉ citing FT; CNBC). Nvidia reports fiscal Q3 after the close on 17 Nov (CNBC). Anthropic's filed range is still $70–78 for 825 million shares, with pricing expected 18 Nov and Nasdaq trading 19 Nov (Anthropic; CNBC). Reuters reported the book six times covered by 12 Nov (Reuters via Investing.com). Indicators. A-1 SIGNIFICANT (carried). A-2 SIGNIFICANT (carried). A-3 ROUTINE (−8.9%, carried). A-4 SIGNIFICANT (−30.7%, carried). A-5 ABNORMAL (carried). Roll-up: 3 Significant = POTENTIAL CRISIS; trend =. Analyst Comment. If today's premarket losses hold, SOX would be close to the 10,000 line in BIZ-50. A cash close at that level would still keep A-4 Significant (25–40%). Leadership uncertainty now sits on top of the earnings risk going into Tuesday.
As of 06:45 ET, FRED's latest values are still for 12 Nov: HY OAS 3.20%, CCC OAS 13.14%, IG OAS 0.89%. The 16 Nov release has not posted yet (BAMLH0A0HYM2; BAMLH0A3HYC; BAMLC0A0CM). Reuters says markets fully price a Fed hike in December, citing CME FedWatch. The 2-year yield had its biggest weekly rise in over two years last week (Reuters via Investing.com). Indicators. C-1 ROUTINE. C-2 SIGNIFICANT. C-3 ROUTINE. C-4 ROUTINE (carried). C-5 ABNORMAL (carried). C-6 ABNORMAL (carried; capped prorations, not suspensions). Roll-up: ENVIRONMENT FOR CRISIS; trend =.
China's commerce ministry described the first US–China Board of Trade meeting on 13 Nov as covering the "$30 billion-for-$30 billion" tariff-cut plan and farm trade, but reported no agreement (CNBC). The truce runs to 10 Jan 2027 (SCMP). China confirmed a Xi–Putin–Trump meeting in Shenzhen on 19 Nov (CNBC). There is still no formal order on the 12 Nov threat to double tariffs on Mexico (Reuters). Indicators. P-1 ABNORMAL. P-2 ROUTINE. P-3 ROUTINE. P-4 ROUTINE. Roll-up: NO CRISIS; trend =.
Friday 13 Nov closes are carried: S&P 500 7,561.67 (−3.3% from its record), VIX 19.30. Monday's cash session had not opened at run time. At 05:08 ET, S&P 500 E-minis were −0.36% and Dow E-minis +0.02% (Reuters via Investing.com). FactSet's Q3 blended EPS growth stays at 31.9% (13 Nov, carried). FOMC minutes are due Wednesday. Indicators. E-1 to E-5 ROUTINE (carried). Roll-up: NO CRISIS; trend =.
Resolved today: none. BIZ-29 (IG OAS ≥1.00, 2–13 Nov, 35%; resolve by 18 Nov) stays open because FRED has not posted the 13 Nov value. The peak through 12 Nov was 0.93, so a miss is very likely. No other BIZ rows are due on or before today.
Due soon: BIZ-29 (18 Nov), BIZ-07 (19 Nov), BIZ-01/04/46/53/54 (20 Nov), BIZ-19/23/30/31/37/41/43/45/47/49/50 (23 Nov), BIZ-52 (24 Nov).
New (dated 2026-11-16; logged in the prediction ledger): - BIZ-55: Any Kpler media briefing dated 17–24 Nov puts the 7-day Total Hormuz Clearance at or below 6,859 kbd (40% of pre-war). 30%, unlikely. Resolve by 2026-11-25. - BIZ-56: By 25 Nov, the White House, USTR or MOFCOM announces an extension of the US–China truce beyond 10 Jan 2027 or implementation of the reciprocal tariff-cut package. 55%, roughly even chance. Resolve by 2026-11-26. - BIZ-57: The S&P 500 closes on 20 Nov below its 13 Nov close of 7,561.67. 45%, roughly even chance. Resolve by 2026-11-23.
UKMTO via Seatrade Maritime and Anadolu; Reuters (via Investing.com, Arab News); Kpler media briefing 16 Nov; hormuz.now; CNBC; RTÉ citing FT; Anthropic; SCMP; FRED (BAMLH0A0HYM2, BAMLH0A3HYC, BAMLC0A0CM); FactSet.
WIRE Business | WIRE Desk | Open-source analysis. Not investment, legal or voting advice. UNCLASSIFIED // OPEN SOURCE.
Every WIRE, every morning. Unsubscribe anytime.
Prefer the website? Subscribe on Substack.
WIRE home · World Instability · Business · Economics · Tech & Cyber · Orthodox · Archive · Subscribe